
There are lots of aspects to maximizing your credit card rewards, including taking advantage of the best welcome bonuses, spending categories, and card perks. Admittedly some of us take maximizing credit cards to the extreme, by having dozens of cards.
Sometimes I think it’s interesting to break down a card strategy by issuer, so in this post I wanted to share my current Citi credit card strategy. Citi has several great credit cards, especially those that earn Citi ThankYou points.
Here’s a rundown of what you need to know to be approved for a Citi card, a summary of my strategy, and then which Citi cards I’m most interested in applying for. In separate posts, I wrote about my Amex card strategy, Capital One card strategy, and Chase card strategy.
How many Citi cards can you have?
There’s no formal limit to how many Citi credit cards you can have. I “only” have three Citi credit cards, though I know plenty of people who have a lot more Citi cards than that. Typically the limiting factor with Citi is the total amount of credit you’ll be extended, rather than the number of cards.
The other big restrictions involve the application process, as I’ll explain below.
Restrictions on applying for Citi cards?
There are a few major restrictions to be aware of when applying for Citi cards…
Citi 8/65 day rule
This is pretty straightforward. Citi will approve you for at most one card every eight days, and at most two cards every 65 days. If you are considering applying for multiple Citi cards, you’ll want to pay close attention to the timing. Note that this doesn’t factor in cards that you apply for with other issuers.
Citi 48-month rule
Citi has the 48-month rule for earning welcome bonuses. If the card you’re applying for mentions the 48-month rule in the application, then you’re not eligible for the bonus on the card if you’ve received a bonus that card in the past 48 months.
As you can tell, the timeline here refers specifically to when you earned the bonus on a card, rather than when you applied for the card. It’s fine if you’re a previous cardmember of a product, but you just can’t have earned a bonus within the past 48 months.
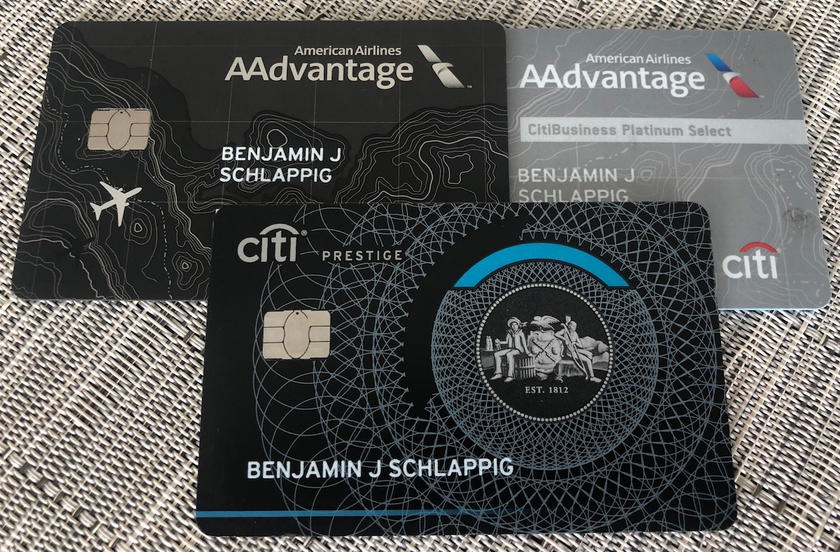
Which Citi cards do I have?
At the moment I have the following three Citi credit cards:
- The Citi Double Cash® Card (review)
- The Citi Prestige Card (review)
- The Citi® / AAdvantage® Executive World Legend Mastercard® (review)
I have the first two cards in order to be able to maximize my Citi ThankYou points, while I have the last card for lounge access, so let me discuss that in a bit more detail.
How do I use my Citi cards?
There are two main reasons that I have Citi credit cards:
- One I have for the ongoing perks that it offers
- Two I have for the return on spending that they offer
Let me explain why I have the three Citi cards that I do in a bit more detail.
The Citi AAdvantage Executive Card is about lounge access
The Citi AAdvantage Executive Card has a $695 annual fee, and is worth it for the lounge access perks it offers:
- The primary cardmember receives a full Admirals Club membership
- You can then add authorized users at the cost of $175 total for the first three (so potentially under $60 each), and $175 for each additional after that; they also get Admirals Club access, and are able to bring up to two guests or their immediate family into Admirals Clubs when flying American or an eligible partner airline the same day
As someone who flies American frequently, I find Admirals Club access to be worthwhile, especially at this cost. Given the cost for authorized users, I have three authorized users on my account, so they can get lounge access as well, and find this to be one of the best value cards for authorized users.
There are other perks that help justify the cost on this card as well, like the ability to earn up to 40,000 Loyalty Points per year, without spending a dime on the card.
The Citi Prestige & Citi Double Cash are about ThankYou points
In general, I like to earn transferable points currencies for my credit card spending whenever possible, since they offer the most flexibility. Within each points currency “ecosystem” (whether it’s Amex Membership Rewards, Capital One, or Chase Ultimate Rewards), there’s the possibility to build up a portfolio of cards so that you can maximize your points earning.
When it comes to earning Citi ThankYou, I have the Citi Prestige Card and Citi Double Cash Card.
The Citi Prestige Card is no longer open to new applicants, but here are the basics of the card:
- The card has a $495 annual fee, but offers a $250 annual travel credit, which to me is more or less worth face value; that means the card is really costing me $245 per year
- The card offers 5x ThankYou points on restaurant purchases, making it one of the best cards for dining; I spend quite a bit on dining, so this is a big category for me
- Having this card allows you to unlock the full value of the Citi ThankYou program, as you can transfer all Citi ThankYou points to airline & hotel partners if you have this card
- The card continues to offer a Priority Pass™ membership with credits at Priority Pass restaurants, which most other cards with Priority Pass™ memberships don’t offer
Then you have the no annual fee Citi Double Cash Card, which I consider to be one of the best cards for everyday spending. The card offers 1x ThankYou points when you make a purchase, and 1x ThankYou points when you pay for a purchase. Earning a total of 2x ThankYou points after paying your bill is an excellent return on spending, and makes this card a keeper.
Now, in all honesty, I don’t actually use the card for my everyday spending at the moment, as I instead direct that spending to the Capital One Venture X Rewards Credit Card (review). However, there’s no reason to cancel the Citi Double Cash — it has no annual fee, and holding onto cards can help your credit score, by increasing your average age of accounts, and lowering your overall credit utilization.
Should I replace the Citi Prestige with the Citi Strata Premier?
As mentioned above, the Citi Prestige Card is no longer open to new applicants. The other popular “premium” card earning Citi ThankYou points is the Citi Strata Premier® Card (review). I keep going back and forth as to whether I’m better off with the Citi Strata Premier or Citi Prestige.
For a bit of background on the $95 annual fee Citi Strata Premier Card, which I consider to be incredibly well rounded:
- The Citi Strata Premier has a generous welcome bonus
- The Citi Strata Premier has great bonus categories, as it offers 3x points on dining, gas and EV charging, groceries, airfare, and hotels
- The Citi Strata Premier offers a $100 annual hotel credit, which in and of itself could cover the card’s annual fee
- The Citi Strata Premier earns the same “premium” ThankYou points as the Citi Prestige, which can be transferred to airline & hotel partners
While the Citi Prestige has a $495 annual fee, it also offers a $250 annual travel credit, so I consider the card to really “cost” me $245 per year. That’s $150 more than I’d pay on the Citi Strata Premier. Is that worth it to essentially earn 5x points on dining rather than 3x points, plus credits at Priority Pass restaurants? The answer is probably “yes” for now, but if the card cuts credits at Priority Pass restaurants, then it might be a different story.
Which Citi cards do I most want?
Admittedly I don’t have the most robust portfolio of Citi credit cards (at least compared to the Chase cards I have), but ultimately I can only have so many credit cards across all issuers. There are a couple more Citi credit cards that it would be nice to have:
- The no annual fee Citi Rewards+® Card (review) interests me because it has an innovative “rounding up” feature on spending, and the card also offers a 10% rebate on redemptions, which can net you up to 10,000 ThankYou bonus points per year
- The no annual fee Citi Custom Cash® Card (review) offers 5x points on your top eligible spending category each billing cycle, on up to $500 of spending per billing cycle; potential categories include drugstores, fitness centers, gas stations, grocery stores, home improvement stores, live entertainment, restaurants, select streaming services, select transit, and select travel
I actually had the Citi Rewards+ Card in 2020, but the account was closed on me due to lack of activity. Oops. While these cards would marginally help me optimize points, the reality is that I probably put enough effort into maximizing my spending, and they might be more trouble than they’re worth.
Bottom line
I currently have three Citi credit cards, which allow me to maximize my Citi ThankYou points and get American Admirals Club access.
I maximize my ThankYou points by having the Citi Prestige Card and Citi Double Cash Card — the former earns me 5x points at restaurants and the latter earns me 2x points on everyday spending. Then I have the Citi AAdvantage Executive Card, which is ideal for Admirals Club lounge access.
How does this compare to your Citi credit card strategy?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.