
In late March we learned the full details of Apple’s new credit card, which was supposed to be launched this summer.
Apple Credit Card Now Open To Applications
As of today the Apple Credit Card is publicly available in the US. Customers can apply for the card through the Wallet app on iPhone in minutes and start using it right away.
Now, spoiler alert — the card isn’t exactly that exciting, in my opinion. It has a couple of unique features, though primarily it will be popular because Apple has such a loyal following, and people will get anything Apple branded. Apple could start selling fax machines and people would be lining up for days to get their hands on one.
Details Of The New Apple Card
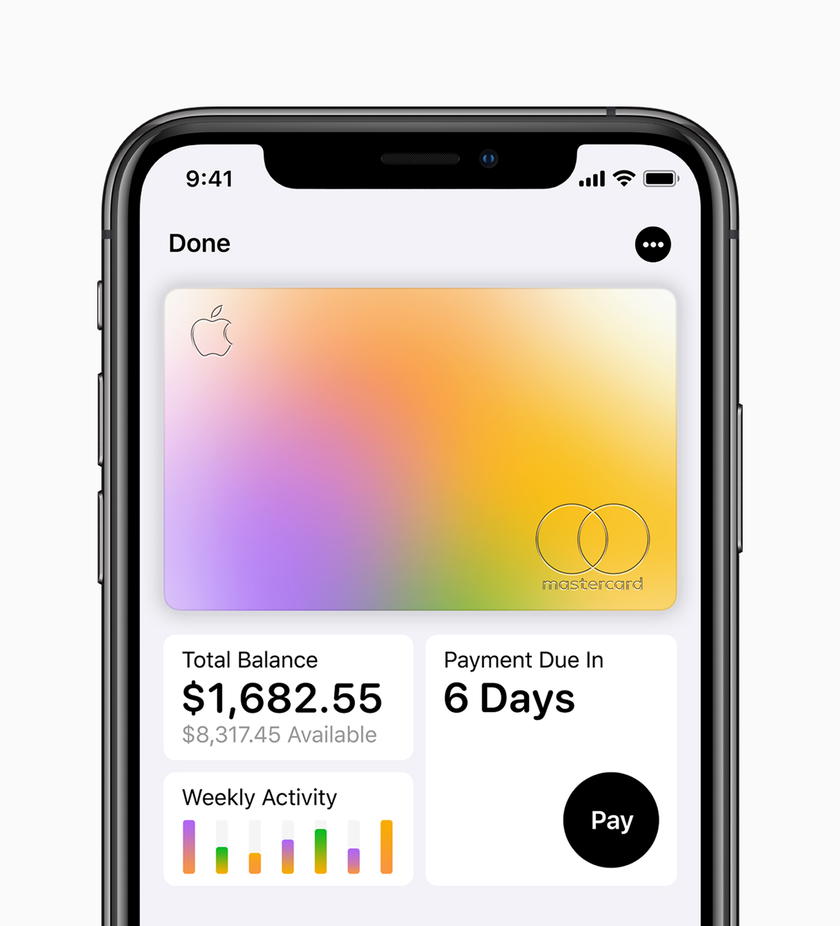
Apple is emphasizing ease of use and privacy as the key features of the card. iPhone users are able to apply directly from their phone, and receive a virtual card number immediately.
Beyond that, Apple is leveraging their data systems to help categorize and label transactions, which they claim will lead to customers living a “healthier financial life” and being better able to understand their spending habits.
Apple Card Rewards Structure
Apple is providing rewards in the form of cashback, which can be earned at the following rates:
- 3% on all purchases made directly with Apple, including at Apple Stores, on the App Store and for Apple services
- 3% cash back on Uber and UberEATS when you use Apple Pay
- 2% when using the Apple Card with Apple Pay
- 1% on physical card purchases made outside of Apple Pay
That’s a decent enough return on Apple and Apple Pay purchases, but there are plenty of rewards cards offering 2% back these days, so the rewards structure of the Apple Card isn’t that interesting to me.

- Earn 3% Cash Back on Dining, Takeout and Eligible Delivery Services
- Earn 3% Cash Back at Drugstores
- Rotating Quarterly Bonus Categories
- $0
- Earn 3% Cash Back on Dining
- Earn 3% Cash Back at Drugstores
- Earn 1.5% Cash Back On All Other Purchases
- $0
- Earn 5% Cash Back at office supply stores on the first $25k
- Earn 5% Cash Back on internet, cable TV, mobile phones, and landlines on the first $25k
- Car Rental Coverage
- $0
- Earn unlimited 1.5% cash back on all business purchases
- Car Rental Coverage
- Extended Warranty Protection
- $0
- 2% cash back on the first $50k then 1% thereafter
- Access to Amex Offers
- No annual fee
- Earn 1% cash back when you make a purchase, earn 1% cash back when you pay for that purchase
- $0
What Makes The Apple Card Different
While the Apple Card seems to fundamentally be a co-branded cashback card, there are a few intriguing differences.
Daily Cash
One of the selling features of the Apple Card is that rewards post relatively “immediately.” This isn’t entirely unique — my Capital One miles usually show up in my account on the same day that I make a purchase — but there are still many issuers and programs that take at least a statement cycle to post.
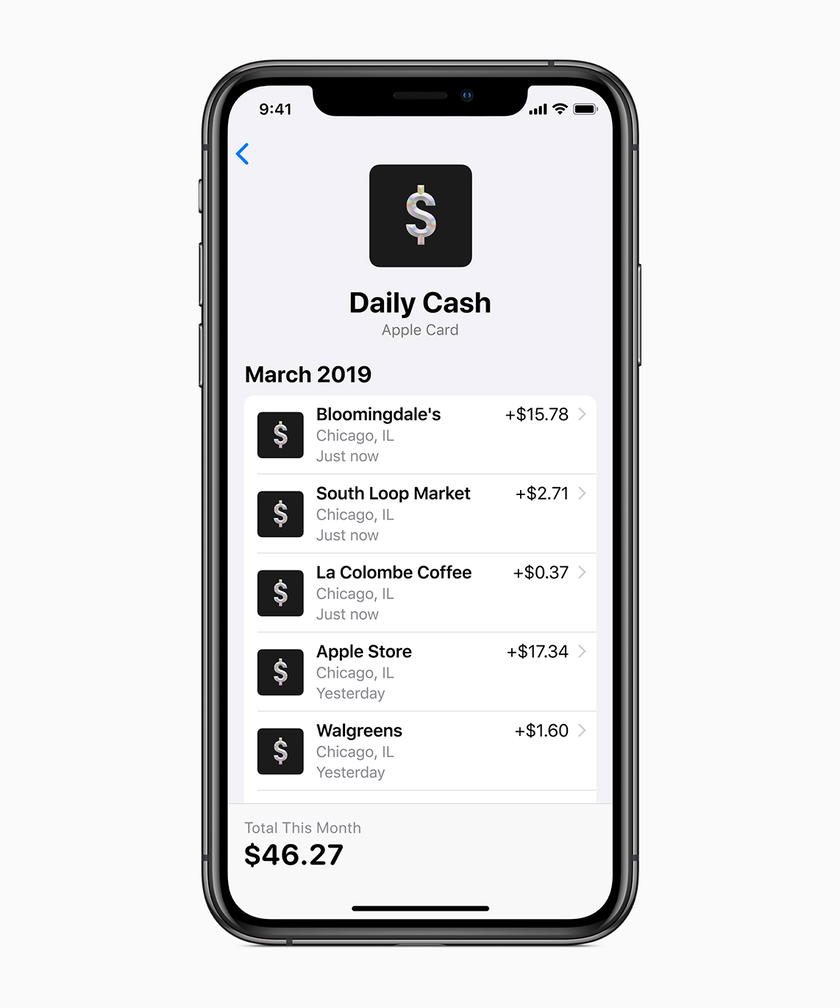
What is interesting about the Apple Card is that the accumulated “Daily Cash” can not only be used for a statement credit (which is common), but because it is integrated with Apple Pay, cardholders can use their cash rewards for other Apple Pay activities, including sending funds to other iPhone users through Messages.
I’m sure nothing could possibly end poorly with that functionality. 😉
Security, Or Hassle?
The Apple Card is obviously focused on mobile payments, and wants to encourage cardholders to use Apple Pay for all transactions.
For retailers that don’t offer Apple Pay, however, a physical card is still being produced. The card is not just of metal, but “titanium,” and doesn’t have any account details on the card:
With no card number, CVV security code, expiration date or signature on the card, Apple Card is more secure than any other physical credit card.
As someone who seems to have their card data compromised fairly often, I appreciate the idea behind not having any account information on the physical card. From a security perspective, that seems smart.
But this is another feature that I see being potentially problematic in practice, as many cashiers are trained to match the last four digits of the physical card against the swipe-generated data. Still, given the paltry 1% return on purchases made outside of Apple Pay, this isn’t really a card I’d recommend using in those cases anyway.
No Fees
Apple is advertising that the card has no fees associated with it, including no annual fee, no late fees, no foreign transaction fees, and no over-the-limit fees. They say that their goal is also to provide interest rates that are among the lowest in the industry. While some of these are nice perks, no foreign transaction fees is a pretty common benefit nowadays.
My Take On The Apple Card
For someone willing to put a bit of effort into maximizing credit card rewards, I think there’s almost no reason to get this card. There are better cards out there in just about all categories (as I’ll outline below).
That being said, I have to give Apple credit for at least putting some thought into the card with the instant rewards, no late fees, no foreign transaction fees, and more.
If this card were being issued by anyone else, I can’t imagine it would be popular. However, Apple has a massive, loyal following, and I imagine this card will take the US by storm, simply because it’s made by Apple.
But there really isn’t anything unique here. It’s not like there aren’t other cards offering nearly instant rewards, and there are plenty of cards you can apply for directly on your iPhone, and there are lots of cards with no annual fees and even no foreign transaction fees.
Alternatives To The Apple Card
If you’re a savvy consumer, you’ll potentially be earning a lot more rewards with other cards. For one, the card’s 1% cashback on non-Apple/Apple Pay purchases simply isn’t competitive, as cards like the Citi Double Cash® Card offer 1% cash back on every purchase, and then an additional 1% cash back when you pay for those purchases (in the form of ThankYou points). The card has no annual fee, so it is an excellent option.
Otherwise, something like the Uber Visa Card offers 4% back on dining, 3% back on hotels and airfare, 2% back on online purchases, and 1% back on everything else, and has no foreign transaction fees and no annual fee.
Of course, if you’re willing to get more than one credit card and are interested in travel rewards, there’s so much more value to be had. I consider the best credit card duo to be the Chase Sapphire Reserve® Card (review) and Chase Freedom Unlimited® (review)
Apple Credit Card Summary
Apple’s new co-branded credit card is now open to new applicants. The card offers 3% cashback on Apple purchases and Uber, 2% cashback on Apple Pay purchases, and 1% cashback on all other purchases. It’s essentially a way to get you to spend more with Apple, and to increasingly use Apple Pay for purchases.
Then it offers some cool perks like instant rewards, no annual fee, no foreign transaction fees, and a cool card without any numbers on it.
When you consider that this card is being issued by Apple, I imagine it’s going to be very popular.
Is anyone applying for the new Apple Credit Card?


Comments are closed.