
Typically when we consider the value of using a credit card to pay for a purchase, we think of it in terms of the rewards that we can earn. However, there’s another major benefit to paying by credit card, and that’s the ability to dispute a charge, or to flag purchases as fraud (this is in addition to any other purchase protection offered by a card).
In this post, I’d like to talk a bit more about disputing credit card purchases. Under what circumstances can you dispute charges, how do you go about doing so, and is there a difference between card issuers when it comes to this? Let’s cover the basics…
When you can dispute a credit card charge
Under what circumstances can you dispute a credit card charge? There are a few general things to keep in mind:
- There’s a difference between a purchase you should mark as fraud, and one you should dispute; fraudulent purchases include completely unauthorized ones, with companies you don’t do business with, rather than maybe a recurring payment with a company you do business with (which you would dispute)
- You’re only supposed to dispute a charge after you’ve reached out to the merchant to resolve the issue, and after you’ve come to a dead-end there
- You often have only 60 days from when the purchase was made to dispute a charge; this can be tricky, especially if you’re paying for a service well in advance (like a flight or a pre-paid hotel)
- Think of a credit card company more as a common sense court, rather than an assistant manager at an Olive Garden; in other words, you don’t dispute a charge because the pasta wasn’t very good, or because the service could have been friendlier, but rather because you didn’t get what you explicitly paid for
To give some examples of when a credit card dispute is appropriate:
- If you didn’t receive what you paid for
- If the item you received is defective
- If you didn’t authorize a purchase
- If you were double charged
- If you were charged a recurring fee after cancelling
- If you were charged the wrong amount
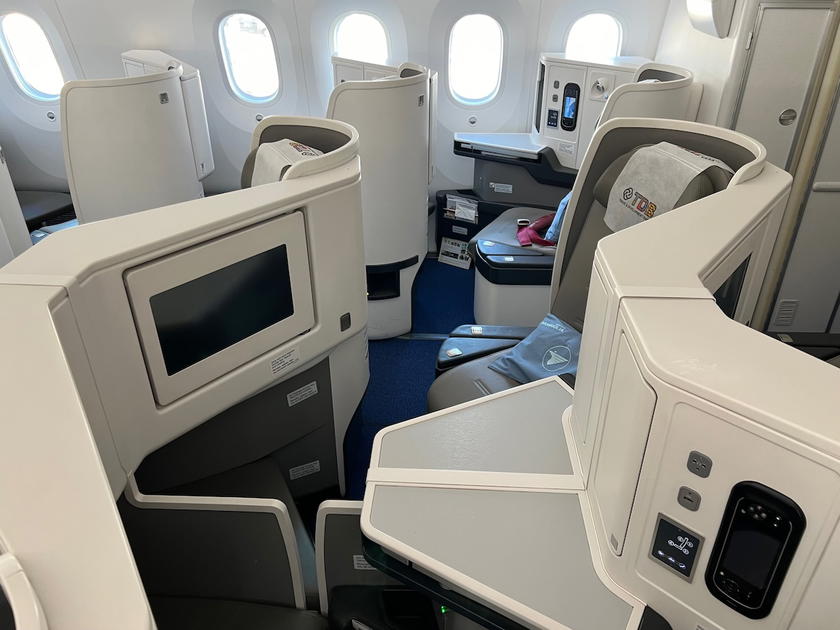
Now, there are definitely some grey areas when it comes to whether something should be disputed or not. For example, say you book a business class ticket on a long haul flight, but the seat is broken and doesn’t recline. Say the airline is only willing to give you a small number of miles as compensation.
Is it appropriate to dispute the charge in that situation or not? While the airline isn’t violating its contract of carriage (which is entirely one-sided), the airline is no doubt not living up to what was advertised, if you were promised a flat bed.
How you can dispute a credit card charge
While each credit card issuer has its own exact procedure for disputing a charge, the general concept is the same:
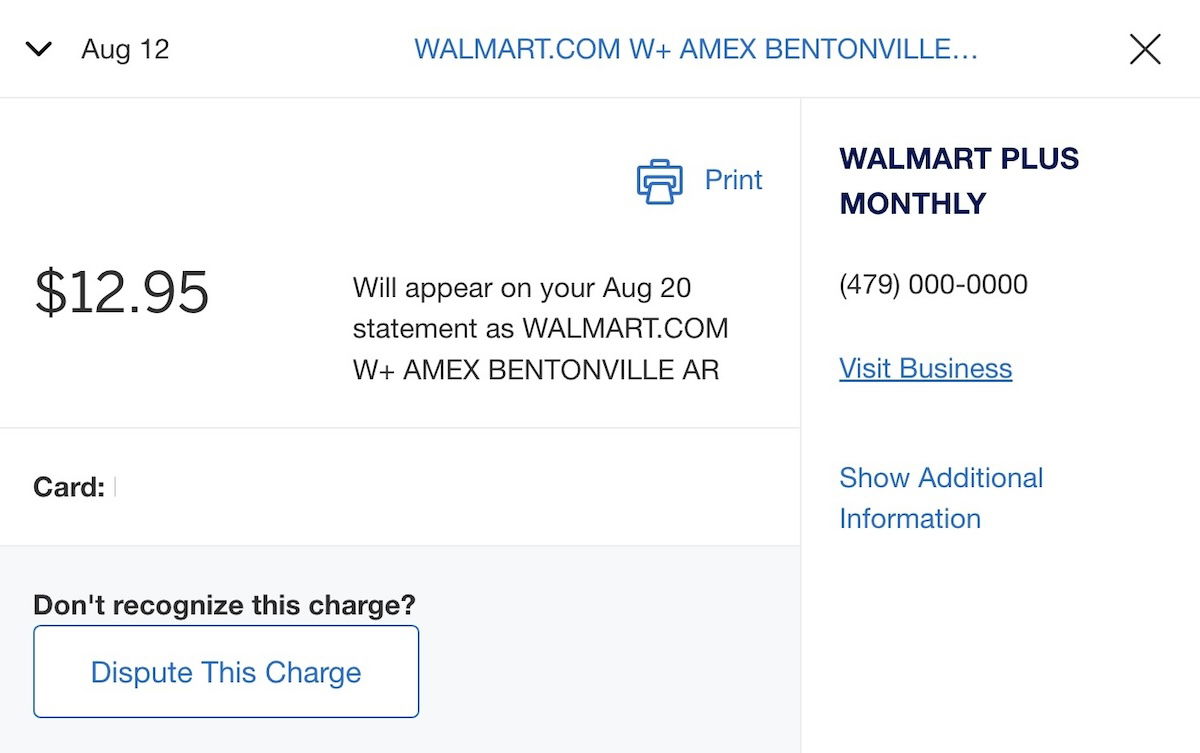
- When reviewing your charges online through your credit card company, you should see some sort of “dispute” button near any eligble purchase, that allows you to dispute the charge
- Alternatively, you can just call the credit card company, and they can help you file a dispute
Typically when you dispute a charge, you’ll be asked to provide some basic details, including confirming that you contacted the merchant first, sharing what went wrong, and more.
When you dispute a charge, you’ll be given a temporary credit for the amount of the purchase, until the dispute is resolved (at which point you’ll either be credited the amount permanently, or will be charged it once again).
The investigation into a charge can take up to a couple of months. This is because the card issuer gives the merchant the chance to respond to the dispute, and that can take some time. So you’ll want to dispute the charge within 60 days, and then you can expect it could take a similar amount of time for a final decision to be made.
Be responsible with credit card disputes
I know many people will dispute credit card charges as their first course of action when they’re not happy, rather than as a last resort. You should always try to first reach out to the company, and only dispute a charge either if you don’t get a satisfactory response, or if you’re approaching the 60-day deadline for disputing a charge.
Just to expand on that a bit:
- If you dispute a charge despite not having first reached out to the company, you might actually be making things take longer, since a dispute takes an extended period of time, while a company can often resolve your issues much more quickly
- While we probably don’t have much sympathy for mega-retailers, for small businesses, credit card disputes can be challenging, since the company isn’t paid until the dispute is resolved
- When you reach out to the company first, you’re really getting two chances at getting something resolved, so it maximizes the odds of a positive resolution
Not all credit card issuers are created equal
On the topic of credit card disputes, here’s what I consider to be an interesting topic. If you’ve disputed credit card purchases with any frequency, you might have noticed that not all issuers handle them equally well. Some issuers are definitely a bit “friendlier” to disputes than others.
For example, in my experience, American Express is the best card issuer when it comes to resolving disputes in a consumer-friendly way. I’ve found Chase to be very good as well. However, I haven’t necessarily had equally positive experiences with other issuers, including Capital One and Citi.
Admittedly this is all anecdotal, and in some situations a dispute is pretty cut and dry, and one party is right, while the other is wrong. However, all else being equal, I find Amex’s excellent handling of credit card disputes to be a reason to use those cards for purchases.
Bottom line
Credit card disputes are a useful tool for situations where a merchant charges you for something you don’t think you should have to pay. While I think it’s important to use this ethically (after reaching out to a company first), this has saved me many times in situations where I got charged for a service that I didn’t receive.
I think it’s also worth emphasizing that different issuers seem to handle disputes a bit differently, and they’re not all equally consumer-friendly.
What has your experience been with credit card disputes, and which issuer have you found to be best?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.