
It has been fascinating to watch the airline industry (particularly in the United States) evolve in the past several years, since the start of the pandemic.
In some ways, the industry came back stronger and faster than expected, which is great. However, I also think the industry has fundamentally shifted, and the only solution may be consolidation (and I’m not meaning to sound like some self-serving airline industry executive, I swear!).
In this post I want to talk about that a bit, including what it could look like, given that I imagine the Trump administration may be friendlier to consolidation than the Biden administration was.
The airline industry is really, really tough
Consumers (including me!) can be tough on airlines, though I think it’s important to acknowledge that the airline industry is an incredibly challenging business, even during good times. It’s one of the most cyclical, capital intensive, low margin businesses out there.
Those who choose to work in the airline industry largely do so out of passion, while those who invest in the airline industry on a long term basis might struggle with math, or maybe just aren’t aware that other industries exist. 😉 Industries don’t get more challenging than this.
People love to claim that airlines are greedy and are these wildly profitable companies earning billions of dollars, but the reality is that this is really consolidated across a couple of airlines, and that’s only during the best of times, while when anything goes wrong, the airlines lose billions.
For that matter, even during the best of times, airlines don’t actually make much money flying passengers. For example, Delta and United both had record years in 2024, yet their cost per air seat mile exceeded their passenger revenue per air seat mile. In other words, airlines made money on their loyalty programs, and from a few other sources (like cargo).
When the topic of industry consolidation comes up, obviously consumers are vehemently opposed to that. I get it. I mean, what consumer would want less choice and less competition? For example, look at JetBlue’s takeover attempt of Spirit, which was blocked by the Department of Justice.
The reason the merger was ultimately blocked is because it was decided that it would be better for consumers if Spirit remained independent as an ultra low cost carrier. The only problem was that Spirit hadn’t made money in years, and had no viable path to profitability.
Now we’ve seen the airline file for Chapter 11 bankruptcy protection, all while completely changing its business model, and retiring planes. Spirit is no longer an ultra low cost carrier, and is reducing industry capacity. That doesn’t seem great for preserving competition, eh?
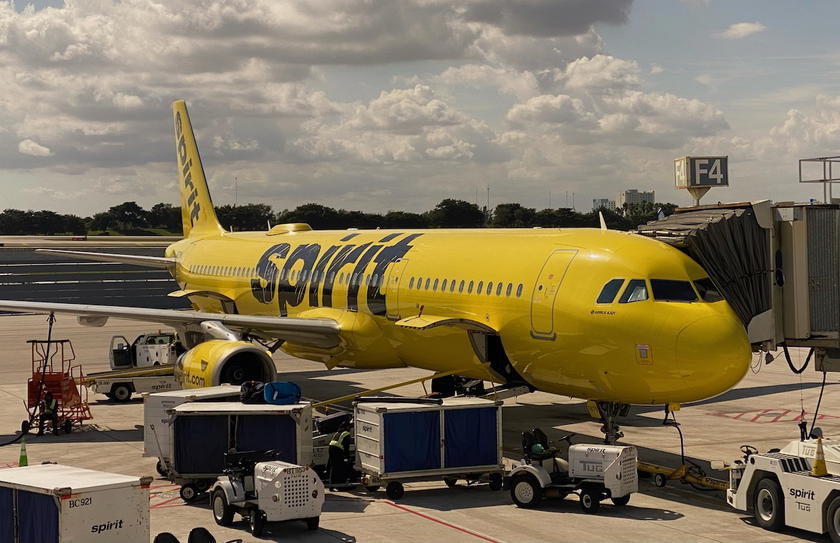
Ultimately Spirit’s cheap ticket prices over the past several years were financed by investors, and that’s just not sustainable.
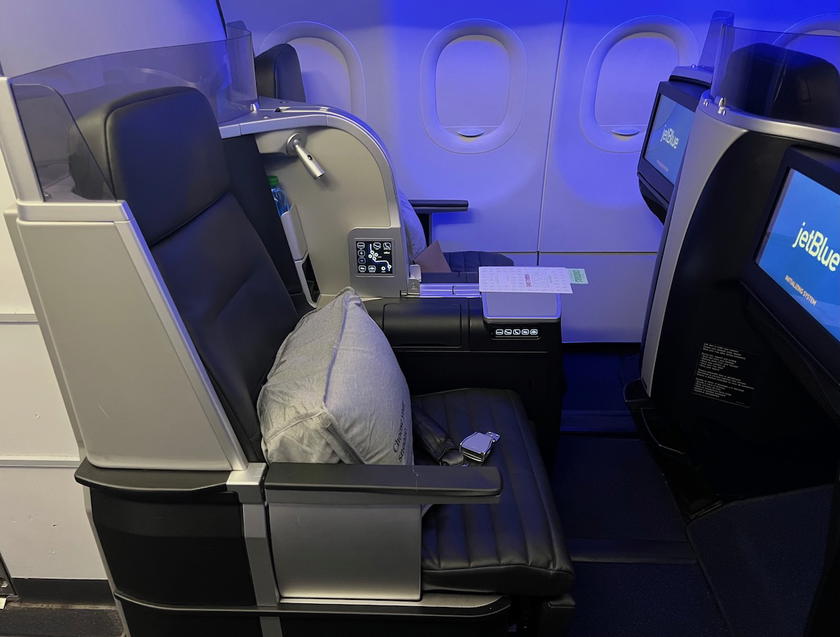
To give a totally different example, take a look at the current situation at JetBlue. It’s an airline that has long tried to offer customers more, from extra legroom, to free Wi-Fi, to seat back entertainment, to drinks and snacks. Yet the airline has also struggled with profitability, because consumers aren’t willing to pay a premium for an all-around better experience.
So now in a bid to return to profitability, JetBlue is trying to cut costs and increase revenue. I can’t blame the airline, but best case scenario, JetBlue could be mildly profitable, despite having a strong position in some of the country’s most lucrative markets (New York and Boston).
Why there’s a profitability “divide” in the industry
Why have a vast majority of the profits in the US airline industry been consolidated at Delta and United, while other carriers struggle with profitability? There are a few factors at play here.
For one, we’ve seen labor costs increase massively in the airline industry since the start of the pandemic. It’s one of the few industries where wage increases have exceeded inflation, at least among some work groups.
I’m really happy for the employees who received pay increases, but there’s no denying that this makes the cost structure of the industry much higher, and it also makes it more difficult to offer low fares. The reality is that demand for air travel is elastic, and if airlines could just raise fares, they would.
These higher labor costs also make it really hard for ultra low cost carriers to compete. Their business models are dependent on consistently growing and having a majority of employees on the lower end of the pay scale, but that just hasn’t been possible with the current state of the industry.
Next, the reality is that much of the profitability at the most profitable airlines comes from loyalty programs, and lucrative co-brand credit card agreements. I’m not suggesting all their profits come from these programs, but the finances at Delta and United would look materially different if it weren’t for SkyMiles and MileagePlus, respectively.
Smaller airlines simply can’t leverage these programs in the same way, since it’s hard to build that level of wallet share when you’re a smaller, regional airline. For that matter, many people collect points with the dream of jetting off somewhere exotic in a premium cabin, and that’s something many smaller airlines can’t offer.
Lastly, at the end of the day, the “big three” US carriers have gotten better at competing domestically, largely offering fares that compete with the value proposition of the lower cost carriers. Aside from loyalty programs, much of their profits come from strong premium demand, including on long haul flights.
They’re able to sell a lot of economy tickets at a loss, simply to fill seats, because it’s better than keeping a seat empty, and also to increase engagement in the loyalty program. That makes it harder for smaller airlines to compete, where they need to make money on each seat they sell, since those domestic economy seats are the core of their business.
People often wonder how ultra low cost carriers are able to succeed in Europe, while it’s a different story in the United States. There are so many factors at play — much lower labor costs, shorter average flight lengths, a more level playing field (since airlines don’t make as much money from their loyalty programs), network carriers with just a single hub (making it more lucrative to serve point-to-point markets), etc.
Is there a solution other than consolidation?
While shareholders subsidizing airline ticket costs is great in the short term, it’s not a long term solution. So, what should be done to address the fact that so many airlines are struggling with profitability?
I think there would be a strong argument against consolidation if we were to go back 15+ years, and undo some of the mergers we saw over time. However, with Delta and United having emerged as the two dominant carriers, it seems hard for any other carrier to come in and stop them. Yes, American could become more competitive, but that’s about it.
The reality is that costs likely aren’t going down. Short of a bankruptcy filing, airlines aren’t realistically going to be able to renegotiate their labor contracts. We’re seeing some airlines try to shrink into profitability, by deferring new aircraft. That’s also not great for consumers in the long run, since less capacity could lead to higher fares. Furthermore, if there’s no growth, then labor costs at airlines continue to go up.
However, it seems to me like consolidation in general is the only practical solution for the profitability problem in the industry. There’s power in scale, from loyalty programs, to route networks, to synergies from reduced costs.
To be clear, this doesn’t have to mean that American, Delta, and United, should just gobble up every airline. However, I do believe that some additional consolidation would ultimately benefit the industry, including potentially creating larger national competitors to American, Delta, and United.
This is what JetBlue tried to do by buying Sprit, but that didn’t work out (and the economics of that deal were questionable to begin with, but that’s a completely different story).
Now, some might be saying “there’s no situation where consolidation is good for consumers.” Well, look at Alaska’s recent acquisition of Hawaiian. Hawaiian was losing money for years, and its prospects were grim. Meanwhile Alaska is in a position where it can better leverage Hawaiian’s assets, and Alaska even plans to launch long haul flights. I’d say this is an example of how a merger can be good all-around.
I swear I’m not trying to be some industry apologist here, but does anyone have a better solution? For example, I think JetBlue is ripe for consolidation, or at a minimum, needs to restart some sort of partnership with American.
Bottom line
The airline industry is a tough business, even during the best of times. Here in the United States, we’ve seen airlines report some record revenue in the past couple of years, but also record costs. While Delta and United are soaring, other carriers are struggling to compete, as they have fewer revenue opportunities than the major global players.
With several airlines continuing to struggle with profitability, I can’t help but feel like some more consolidation is inevitable… and it might not even be bad for consumers!
What’s your take on airline industry consolidation? Do you think we’ll see more?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.