
A longtime reader sent me an email with a question that I figured it makes sense to address here, since I know many are probably in the same boat.
How do you decide when to apply for more credit cards?
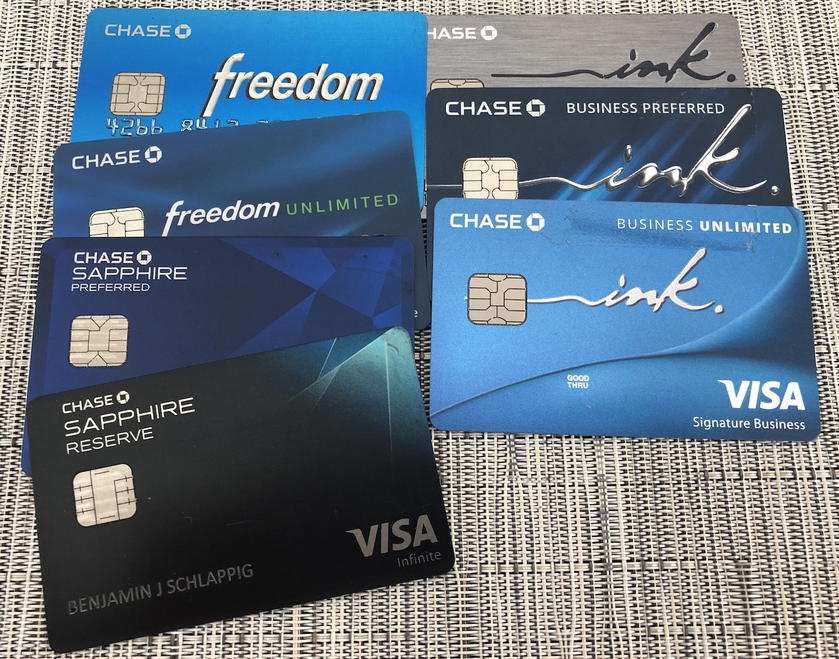
A reader in his mid-20s has an excellent credit score, and picked up the Chase Sapphire Reserve® Card (review) last year. He has over 100K Chase Ultimate Rewards points, which he wants to keep building up. He says he can basically get any card he wants, but he’s not sure where to go from here:
- He’s not a huge credit card spender, so realistically he’s not going to be splitting his spending between a dozen cards
- He’d like to take advantage of some of the great credit card bonuses out there, but also doesn’t want to open and close cards (understandably), and also doesn’t want to rack up too much in annual fees
With that out of the way, how do you decide whether to open a new card, and which offers to take advantage of?
My philosophy on building up a credit card portfolio
Let me start with an important warning — only apply for more credit cards if you can use them responsibly. If you’re going to end up overspending and financing charges, you’re unlikely to come out ahead. With that out of the way, I have two general thoughts if you’re in a situation where you have a good credit score but a limited number of credit cards.
First of all, when it comes to opening credit cards (and most things in life, for that matter), slow and steady wins the race. If you’re starting with just one credit card, I don’t recommend suddenly applying for 10 credit cards at once, because that has the potential to significantly impact your credit score. This is especially true early in your credit card journey, if you have just one or two cards.
Second of all, in the long run, having lots of credit cards can absolutely help your credit score. I have over two dozen credit cards, and my credit score is nearly prefect. You’ll want to be sure that you make your payments on-time, but beyond that, having more cards can help your credit score:
- Having more credit cards increases your total available credit, allowing you to potentially lower your credit utilization (the percentage of your available credit you use); this makes up 30% of your credit score
- Having more credit cards for a long time can help your average age of accounts, and for that matter the more cards you have, the less your average age of accounts is impacted by opening a new card; this makes up 15% of your credit score
The only other consideration is that applying for a credit card will get you an inquiry on your credit report, and that can temporarily ding your score by a few points. However, that shouldn’t be an issue in the long run.
How would I decide which cards to open?
If I had a great credit score but only one credit card and fairly limited credit history, I’d probably apply for one or two cards ASAP. I recommend doing this soon, because like I explained above, this will help further establish and stabilize your credit profile.
My focus wouldn’t necessarily be on getting the cards with the very biggest welcome offers, but rather my focus would be on getting cards where I see value, and that I could see myself holding onto long term. And if I wasn’t sure if I could get value from the cards long term, I’d probably consider a card where I know there’s a downgrade option after a year.
An ideal card could be one with strong ongoing perks that more than justify the annual fee, or it could be a no annual fee card, as it’s great to have cards you can hold onto for years and years at no cost, to help build your average age of accounts.
The way I see it, there are a few different strategies to take here…
Given that the reader already has the Chase Sapphire Reserve® Card, it could be worth picking up the no annual fee Chase Freedom Unlimited® (review). The card offers a minimum of 1.5x points on all purchases, so it’s one of the best cards for everyday spending. This could be a great card to hold onto long term to build the reader’s credit score, and could also help maximize spending to earn more Chase points.
Hotel credit cards are also easy to justify, in my opinion. For example, I’d consider picking up the $150 annual fee IHG One Rewards Premier Credit Card (review), which has a phenomenal welcome bonus, and offers an anniversary free night certificate, IHG One Rewards Gold status, and much more. This should more than justify the annual fee on an ongoing basis, but if it doesn’t, it should be possible to downgrade to the no annual fee IHG One Rewards Traveler Credit Card (review).
I also think it’s good to diversify card issuers a bit, so if it were me, I’d consider picking up the duo of the $95 annual fee Citi Strata Premier® Card (review) and the no annual fee Citi Double Cash® Card (review). The two cards are excellent complements and have big bonuses.
You can even transfer Citi ThankYou points to some of the same partners as Chase Ultimate Rewards. If after a year you decide you don’t want to pay the annual fee on the Citi Premier Card, you have downgrade options.
There are obviously plenty of other options out there, but this is just an example of a few different directions you can go.
Bottom line
It’s exciting to have a great credit score and get approved for your first “big league” credit card. It can be tough to decide what to do from there, though, especially while trying to maintain (or even improve) your credit score.
Having more credit cards (and using them responsibly) can absolutely help your credit score over time, but I’d recommend taking a slow and steady approach. If I just had one or two cards, I’d recommend applying for one or two additional cards that you plan to keep in the long run. These could be no annual fee cards, or cards that offer perks that more than offset the annual fee.
Then see how things go — you’ll probably be pleasantly surprised by how your credit score and overall credit profile evolves, so hopefully after another six months or so you can pick up some more cards. But I think that’s a good start.
If anyone has similar experiences or tips, feel free to share them below!


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.