
There are all kinds of travel rewards credit cards out there — there are transferable points cards, there are airline credit cards, and there are hotel credit cards. When it comes to the value of holding onto credit cards without much spending, I’d say that hotel credit cards represent the best value, on balance.
That’s definitely the case if you’re loyal to a particular hotel loyalty program, but it’s even the case for those who are “free agents,” meaning those people who don’t have elite status with a hotel loyalty program, and aren’t otherwise usually loyal to a hotel group.
Let me explain why, though let me emphasize that I’m not suggesting you should use these cards for everyday spending. If you want to maximize your travel rewards, I recommend using cards earning transferable points currencies, like the Chase Sapphire Preferred® Card (learn more), Citi Strata Premier® Card (learn more), or American Express® Gold Card (learn more). Not only do these cards give you the most flexibility, but they also often have valuable bonus categories on spending.
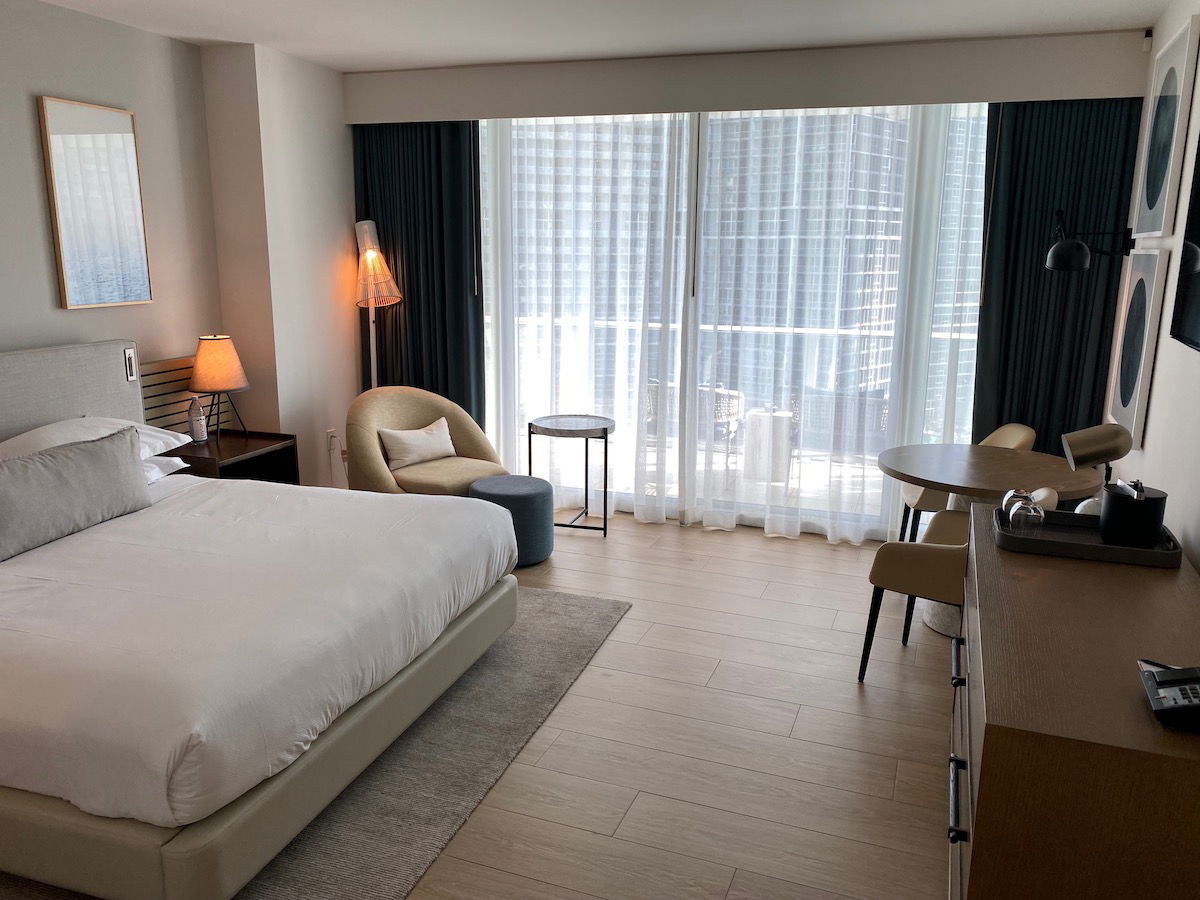
Mid-range hotel credit cards largely pay for themselves
Great welcome bonuses aside, in general I think airline credit cards are primarily worth it if you’re at least somewhat loyal to an airline. That’s because these cards often have benefits when flying with a particular airline, but the cards don’t really “pay” for themselves.
What makes hotel credit cards unique is that they can often be worth holding onto even if you don’t spend money on the cards, thanks to the free night certificates and elite status they potentially offer. For example, take mid-range hotel credit cards, each of which offers an anniversary free night certificate:
- The $150 annual fee The New IHG One Rewards Premier Credit Card (learn more) and $200 annual fee The New IHG One Rewards Business Credit Card (learn more) offer a free night certificate on your account anniversary every year, valid at a property costing up to 50,000 points; you can use points to top-off those awards
- The $95 annual fee World of Hyatt Credit Card (learn more) offers a free night certificate on your account anniversary every year, valid at a Category 1-4 property
- The $125 annual fee (Rates & Fees) Marriott Bonvoy Business® American Express® Card (learn more) offers a free night certificate on your account anniversary every year, valid at a property costing up to 35,000 points; you can use up to 15,000 points to top-off those awards
Obviously hotel free night certificates are most valuable if you have top-tier elite status with a hotel group, since you can get perks like free breakfast and suite upgrades. However, even without that, odds are that if you travel with any frequency, you’ll easily be able to get outsized value on your credit card annual fee with just one free night certificate stay.
With how expensive hotel stays are nowadays, it’s rare to find a hotel in the United States retailing for less than $100 per night. For example, I’m not in any way loyal to IHG, but I’ve consistently been able to use IHG free night certificates at properties costing $200+ per night, and that’s without any sort of a points top-off.
And that’s only the tip of the iceberg with these cards, as they often have plenty of other perks, ranging from elite status, to discounts on award redemptions, and more. Just to give an example of how robust card benefits can be, the IHG One Rewards Business Card offers IHG One Rewards Platinum status for as long as you’re a cardmember, a fourth night free on award redemptions, up to $100 in annual IHG food & beverage rewards, up to $50 in United TravelBank credit each year, and much more.
Premium hotel credit cards can offer next-level perks
As you can see above, I tend to think the mid-range annual fee hotel credit cards are sort of the sweet spot, given how little effort is needed to extract outsized value. However, I tend to think the ultra-premium hotel credit cards potentially offer even more value, though also require more effort.
For example, the Hilton Honors American Express Aspire Card (learn more) has a $550 annual fee (Rates & Fees), but offers huge perks, including:
- Hilton Honors™ Diamond Status for as long as you have the card
- A free night award valid for a standard room at a vast majority of Hilton Honors properties in the world
- Up to $400 in annual Hilton resort credits (get up to $200 in statement credits semi-annually for eligible purchases made directly with participating Hilton Resorts.)
- Up to $200 in annual flight credits (get up to $50 in statement credits each quarter, for a total of up to $200 back each year, on flight purchases made directly with an airline or through AmexTravel.com)
Similarly, the Marriott Bonvoy Brilliant® American Express® Card (learn more) has a $650 annual fee (Rates & Fees), and offers several benefits, including:
- Marriott Bonvoy® Platinum Elite Status for as long as you have the card
- A free night award valid for a property costing up to 85,000 points per night; you can top-off these awards with up to 15,000 points
- Up to $300 in annual restaurant credits, in the form of a $25 monthly restaurant credit
While it takes a bit more effort to recoup the annual fees on these cards, it’s also much easier to come out way ahead, especially with the higher tier status, the more valuable free night awards, and more.
Two other reasons to get hotel credit cards
Beyond the actual ongoing perks of having hotel credit cards in the long-run, there are two other reasons that these cards should be no-brainers for most consumers.
First of all, these cards often have huge welcome bonuses, that are often worth $1,000 or more, by my valuation of points. That’s a huge upfront reward for picking up a card.
Beyond that, a big part of maximizing credit card rewards is making sure you have a great credit score. Keeping credit cards open in the long-run helps your credit score, by increasing your average age of accounts, lowering your credit utilization, increasing your good payment history, and more.
Obviously most people want to minimize the cost of holding onto credit cards, which means you’ll either want to consider no annual fee cards, or hotel credit cards that offer outsized value just for being a cardmember. I think hotel credit cards are pretty unbeatable for this purpose, given the value they offer.
Bottom line
Even if you’re not loyal to a specific hotel group, I tend to think that hotel credit cards are worth picking up. Assuming you travel with any frequency, you’ll almost certainly end up at a destination where a hotel credit card free night certificate will get you outsized value.
The free night certificate alone should more than justify the annual fee on many mid-range cards, and that’s only the tip of the iceberg. Hotel credit cards offer plenty of other perks, including elite status.
To those who aren’t loyal to a specific hotel group, do you still see value in hotel credit cards?
The following links will direct you to the rates and fees for mentioned American Express Cards. These include: Marriott Bonvoy Brilliant® American Express® Card (Rates & Fees), Marriott Bonvoy Business® American Express® Card (Rates & Fees), and Hilton Honors American Express Aspire Card (Rates & Fees).


Depends on the program/card. For the major 4 US brands... Hilton's Aspire mostly-uncapped FNC, still winning. Marriott's Brilliant 85K certificate + 25K points, not so much (especially when aspirational properties know to start award rates at 111K to avoid those attempting to redeem there.) WOH needs to actually do a premium card, finally (Cat 1-4 has been so devalued that most worthy properties start at Cat 5, think Grand Hyatt at SFO, etc.) IHG recent...
Depends on the program/card. For the major 4 US brands... Hilton's Aspire mostly-uncapped FNC, still winning. Marriott's Brilliant 85K certificate + 25K points, not so much (especially when aspirational properties know to start award rates at 111K to avoid those attempting to redeem there.) WOH needs to actually do a premium card, finally (Cat 1-4 has been so devalued that most worthy properties start at Cat 5, think Grand Hyatt at SFO, etc.) IHG recent updates to cards are mostly increased AF + coupon credits (not great, not terrible), but at least the 50K free night (previously 40K) 'discount' is uncapped (can add as much as you want), so it's basically a $250 discount (at 0.5 cpp).
I don't know about the US hotel market, but Accor is the only global chain which is competitively priced in most places most of the time. No point chasing a 'free' night at the Marriott by the obelisc in BsAs where a basic room retails at $544 (!) when the NH across the road will sell you a junior suite for $200.
I generally agree with this article. I think it also draws attention to what is valuable: if you're signing up for a credit card, you're doing it for a purpose and desired benefit set.
What I loathe about premium cards of late is that they pre-select what value looks like on things motivated by subsidies. Walmart+, Peloton credits, Lyft credits you only get after 3 monthly rides, Blade/Uber credits for a small percentage of...
I generally agree with this article. I think it also draws attention to what is valuable: if you're signing up for a credit card, you're doing it for a purpose and desired benefit set.
What I loathe about premium cards of late is that they pre-select what value looks like on things motivated by subsidies. Walmart+, Peloton credits, Lyft credits you only get after 3 monthly rides, Blade/Uber credits for a small percentage of any ride, travel-portal-only credits with substantially higher cancellation fees and no loyalty benefits, etc. It's like... if you have to chase 47 pennies in the couch to tell yourself that you're getting value from something, the thing you don't clearly value is your time.
Which is my new perspective on many "elite" credit cards. They don't impress anyone, they are extracting value away from you via direct and indirect methods, and it's a suckers game to hold onto them for any period of time > 1 year.