
It’s an exciting time for the Citi ThankYou ecosystem, as we’ve recently seen American AAdvantage added as a transfer partner, plus we’ve seen the launch of some new cards.
For those who use American’s co-branded credit cards for their spending, I think one common question is whether it makes sense to instead use Citi ThankYou credit cards, and then transfer those points to American AAdvantage. In this post, I’d like to talk about that in a bit more detail, as it’s something I’m thinking about as well…
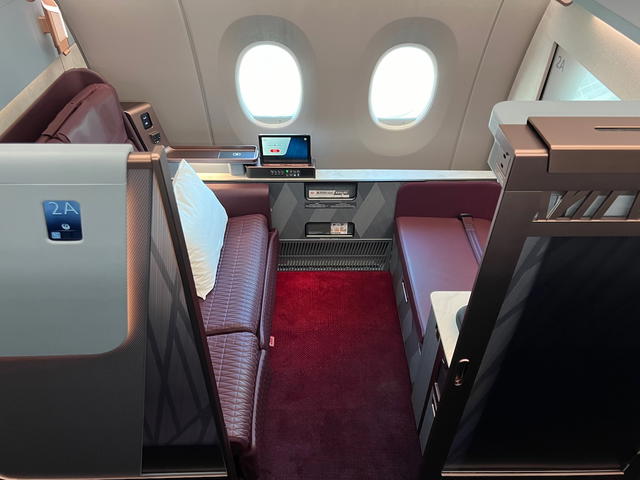
American AAdvantage credit cards earn Loyalty Points
American AAdvantage has the Loyalty Points system for earning elite status, whereby the elite status you earn is based exclusively on how many Loyalty Points you rack up in a membership year. For example, AAdvantage Gold status requires 40,000 Loyalty Points, while AAdvantage Executive Platinum status requires 200,000 Loyalty Points.
Arguably the easiest way to earn Loyalty Points is with credit card spending. Every dollar spent on an eligible co-branded AAdvantage credit card earns one Loyalty Point. This includes cards like the Citi® / AAdvantage® Executive World Legend Mastercard® (review), Citi® / AAdvantage Business™ World Elite Mastercard® (review), etc.
So you have lots of people who spend money on American’s co-branded credit cards specifically to earn status. Of course they also earn AAdvantage redeemable miles, but there’s no denying that if you take the Loyalty Points out of the equation, other cards potentially have much more lucrative rewards structures.
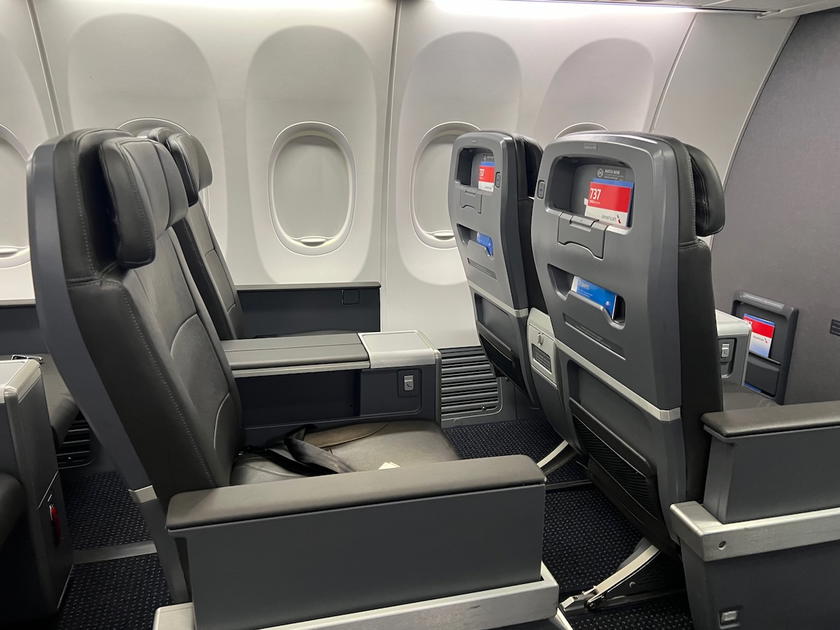
Citi ThankYou credit cards have better rewards structures
In the past, co-branded American cards were the only efficient way to earn AAdvantage miles with credit card spending. However, thanks to a recent change, it’s now possible to transfer Citi ThankYou points to American AAdvantage at a 1:1 ratio, assuming you have the Citi Strata Elite℠ Card (review) or Citi Strata Premier® Card (review).
Assuming you have one of those cards, then you can pool all your Citi ThankYou points, and transfer them all to American AAdvantage at that ratio. For example, this also means that rewards earned on the Citi Double Cash® Card (review) could be moved to AAdvantage, assuming you have the card in conjunction with one of the above.
This is a pretty unbeatable no annual fee card — it offers 1x ThankYou points when you make a purchase, and 1x ThankYou points when you pay for that purchase, meaning you can earn up to 2x ThankYou points per dollar spent, after paying the bill. There aren’t any co-branded American cards that earn you more than 1x AAdvantage miles on non-bonused spending.
There’s simply no denying that you’re going to rack up AAdvantage miles at a much quicker rate through the Citi ThankYou ecosystem, rather than through American AAdvantage. Similarly, some of the premium cards have great bonuses categories. The Citi Strata Premier Card has valuable bonus points categories, and offers 3x points on dining and restaurants, gas stations and EV charging, supermarkets, airfare, and hotels.
The catch is that if you move Citi ThankYou points to American AAdvantage, those points transfers don’t qualify as Loyalty Points. So really, the question becomes about your relative valuation of AAdvantage redeemable miles vs. AAdvantage Loyalty Points.
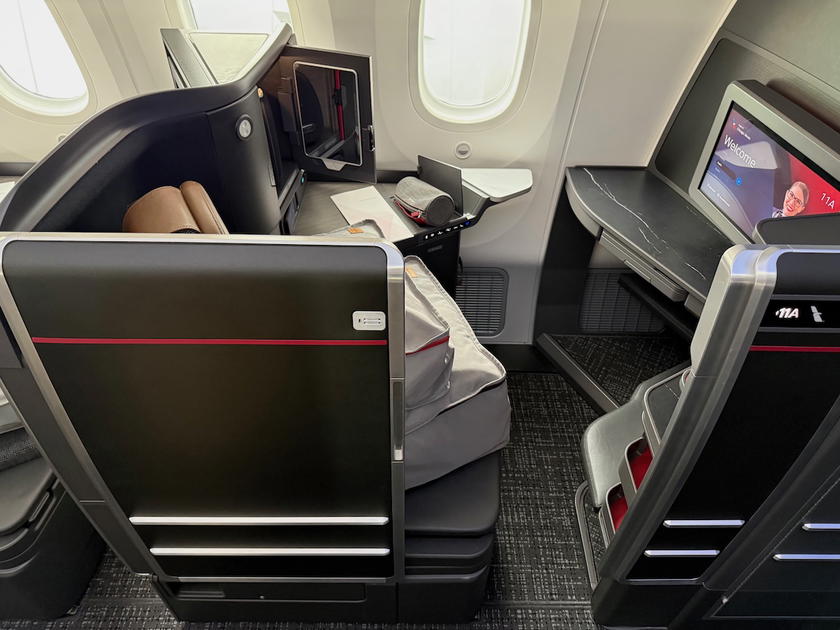
What’s the best way to go about doing the math on this?
I’d argue that the way American AAdvantage has joined Citi ThankYou is pretty smart, in terms of avoiding cannibalizing its own credit card business too much.
While there’s a bit more nuance to it, those looking to earn American AAdvantage miles for credit card spending now have a pretty straightforward question. For every dollar spent (and after paying the bill), would you rather earn:
- 1x AAdvantage miles and 1x Loyalty Points per dollar spent, with a co-branded American card
- Or a minimum of 2x AAdvantage miles per dollar spent, along with lots of other bonus categories that are more lucrative
The opportunity cost for spending on American’s co-branded credit cards has long been there. However, the comparison is now more direct than ever before, since you can earn the same mileage currency, just at a much faster rate.
There’s no right or wrong answer, though I will say that I think people often irrationally pursue airline elite status, despite the fact that its value has decreased massively over the years. That’s primarily because airlines have gotten better at monetizing first class, so it has become much tougher to snag a complimentary elite upgrade to first class.
Let’s say you’d spend $200,000 per year on an American card to earn Executive Platinum status. Let’s say you’d earn 200,000 AAdvantage miles on that spending, and let’s say you could otherwise earn a minimum of 400,000 AAdvantage miles by instead spending on Citi ThankYou cards.
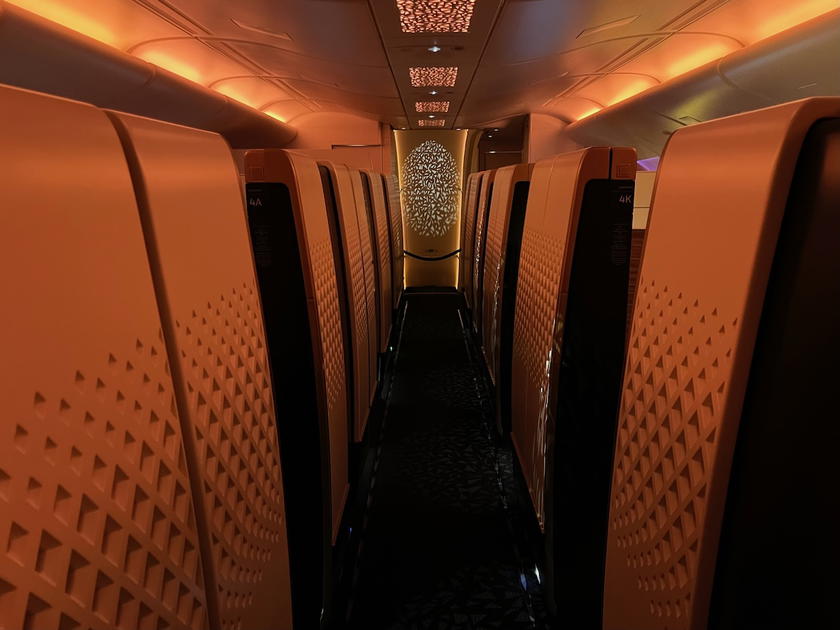
The question becomes, how many miles would you pay for Executive Platinum status, and what are you really getting for that? Alternatively, the incremental additional miles that you earn through Citi ThankYou would be nearly enough for a roundtrip Etihad A380 first class ticket from Toronto to Abu Dhabi.
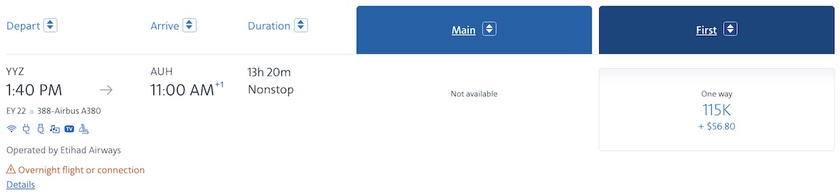
That’s a pretty awesome incremental perk, no? That says nothing of the fact that earning Citi ThankYou points gives you so much more flexibility, since you can use them for all kinds of other redemptions as well.
I think often people overvalue the perks of elite status, while undervaluing the potential value of the points and miles that they’re forgoing by choosing to spend their way to status.
Now, while that’s my take, let me actually admit my own quasi irrationality. I had AAdvantage Executive Platinum status for 14 years, and I finally dropped down from that status this year. It’s not that I’m not capable of completing the credit card spending. Instead, I just couldn’t bring myself to spend with such an opportunity cost, because the perks of the status were limited.
I found very few upgrades to be clearing, and I typically managed to secure a premium cabin seat at a reasonable cost, whether with miles, or as a discounted cash upgrade.
That being said, I’m not totally over status. I actually do value oneworld Emerald status immensely, perhaps even irrationally. That’s because I love all the amazing lounges and priority services that offers when flying with other oneworld airlines.
So I’ve updated my strategy to be more efficient:
- I’m now just pursuing AAdvantage Platinum Pro status, rather than Executive Platinum status; that requires 125,000 Loyalty Points, rather than 200,000 Loyalty Points
- I’m only qualifying for status every two years; the elite membership year starts in March, so I’m front loading my spending on American cards around that time to earn status as soon as possible, which is then valid through the end of February two years later, before starting the process over again
In other words, my goal has gone from earning 200,000 Loyalty Points every year, to instead earning 125,000 Loyalty Points every second year.
For all that additional spending, I’d rather use a card that maximizes my return on spending, like the Citi Double Cash Card. After all, I enjoy Etihad’s A380 first class more than I enjoy being the third person to miss an upgrade on an El Paso to Dallas flight.
Bottom line
With Citi ThankYou points now being transferable to American AAdvantage, the direct opportunity cost of spending on American’s credit cards has increased. That being said, Citi ThankYou points don’t earn you American Loyalty Points.
So the question comes down to how much you value additional redeemable AAdvantage miles vs. Loyalty Points. For those looking to earn American miles, there’s a strong case to be made for using a combination of the Citi Strata Premier Card and Citi Double Cash Card to maximize rewards.
Sure, that spending might not earn you status, but everyone should think about what incremental perks they’re actually getting from status, compared to how they could redeem extra miles for nice travel experiences.
To American flyers, has your credit card spending strategy changed as a result of the Citi ThankYou situation?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.