
A couple of weeks ago I wrote a post about the 21 credit cards that I have right now. When people who aren’t miles & points enthusiasts find out how many cards I have they’re often shocked, though I’d like to think my card portfolio is easy to justify, given the benefits I get. Yes, I actually pay a lot in credit card annual fees, but I’d like to think that I get more back in value.
Reader Andrew H left the following comment on that post:
I count a total of $3,187 in annual fees on those 21 cards on a yearly basis. That’s wild. Only 4 of your cards have no annual fee. You travel all the time so most of these make sense but I have to think that you got some of these just for the bonus and will cancel.
It’s an interesting point, so in this post I wanted to do an analysis of my card portfolio, and in particular how I can justify the card annual fees. How much of those annual fees do I allocate to helping me maximize the points I earn for my credit card spend, and how much of those annual fees do I allocate to the long-term perks offered by the cards, which have nothing to do with how much I spend on the cards?
My ~$2,800 in credit card annual fees
First, here’s a chart with some of the cards that I’ve had for at least 12 months, along with the annual fees, starting with the most expensive:
 American Express Platinum Card®
 Citi® / AAdvantage® Executive World Legend Mastercard®
 The New IHG One Rewards Premier Credit Card
 The Blue Business® Plus Credit Card from American Express
 Ink Business Cash® Credit Card
 Ink Business Unlimited® Credit Card


As you can see, this includes many cards, and doesn’t include a few of the cards that I’ve acquired within the past year, which I haven’t necessarily decided what to do with yet.
It goes without saying that this is a lot of money to spend on annual fees. I also realize I travel a lot more than most, and that I’m fortunate to be in a position where I can pay this much in credit card annual fees (even if the numbers check out). In addition to helping me maximize the points I earn for credit card spend, these cards offer all kinds of additional perks, including the following (Enrollment is required for select benefits):
- A fourth night free hotel benefit, that saves me thousands of dollars per year
- Annual travel credits — a $300 annual travel credit, a $250 annual airline credit, a $200 annual airline fee credit, up to $219 back on a CLEAR+ membership every year
- Anniversary free night certificates — two with Marriott, one with IHG, and one with Hyatt
- Other annual credits — an up to $200 annual Uber credit
- Access to Amex Centurion Lounges, Delta Sky Club®, American Admirals Clubs, and Priority Pass™ lounges
I’d rather allocate annual fees to perks than bonus categories
When doing this numbers exercise, I’d always rather allocate annual fees to perks rather than the bonus categories offered by cards. Furthermore, my goal isn’t to put an exact dollar value on perks, but rather to look at whether or not they cover the annual fee.
There are a couple of reasons for this. First of all, the reason I don’t provide an exact number value for what I think the perks are worth is because that can vary year-to-year. When I use a hotel free night certificate on a card with a $75 annual fee, I might have redeemed that two years ago for a night that would have cost $400, while I redeem it last year for a night that would have cost $200. For me the key detail in doing the math is to acknowledge that I’m getting more value than what I spent, which is the case in both years. This is an ongoing analysis that needs to check out every year, or else I’ll cancel a card.
I also prefer allocating the fees to perks whenever possible because I find that makes the math easier. That’s because the value of bonus categories is highly relative. In other words, I would value a card differently that earns 5x points in a specific category based on whether the alternative is a card that earns 3x points or a card that earns 1x points.
Annual fees I allocate to perks
As I explain my justification for having a card, I’ll share the amount of the annual fee I allocate to the perks. Then in the next section we’ll look at what cards that leaves, and how I allocate that to the cards’ rewards for spend.
So here we go…
American Express Platinum Card® has a $895 annual fee, and I’d say I value the up to $200 annual airline fee credit and up to $200 annual Uber credit, 80% of that for a value of $320. Then I easily get another $150 of value from the lounge access offered by the card, including Centurion Lounge access, Delta Sky Club access, and a Priority Pass™ membership. And don’t forget up to $219 back on a CLEAR+ membership every year. On top of that, I get 5x points on airfare (on up to $500,000 in flight purchases per calendar year and then 1x when booked directly with the airline or through Amex Travel), which is the icing on the cake. (Enrollment is required for select benefits)
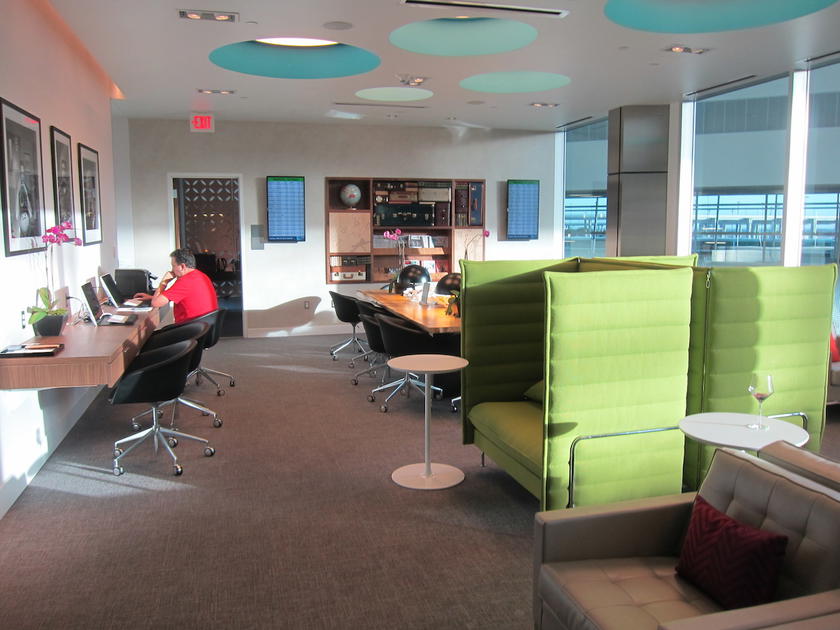
The Platinum Card® comes with Amex Centurion Lounge access
The Citi Prestige Card has a $450 annual fee, and offers a $250 annual airline credit, so the real out of pocket on the card is $200 per year. I save literally thousands of dollars per year on the card using the fourth night free hotel benefit, though obviously I spend more on hotels than most. So that covers the annual fee.
I’ve saved a lot of money with the Citi Prestige fourth night free benefit
The Chase Sapphire Reserve is a card I have primarily for spend, but it does offer a $300 annual travel credit that’s more or less worth face value, since it can be applied towards any travel coded purchase. Since the card has a $795 annual fee.
The Citi® / AAdvantage® Executive World Legend Mastercard® is a card that I have primarily for lounge access but don’t actually spend much money on. The card has a $695 annual fee and offers an Admirals Club membership for the primary cardmember.
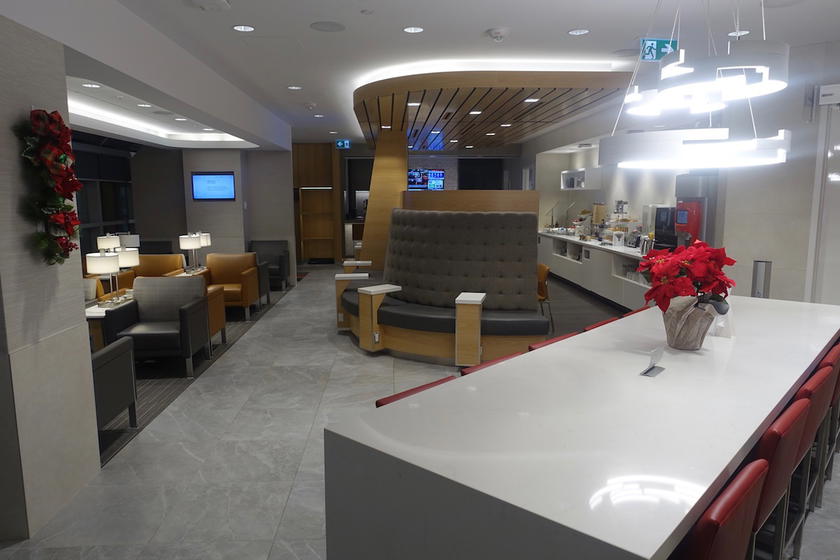
The Citi AAdvantage Executive Card offers Admirals Club access
The Marriott Bonvoy American Express Card and Marriott Bonvoy Business® American Express® Card ($125 annual fee (Rates & Fees)), and each offer an anniversary free night certificate valid at a property retailing for up to 35,000 points per night. I value that more than the annual fee.
The World of Hyatt Credit Card (which has a $95 annual fee) offers an anniversary free night certificate valid at a Category 1-4 property, which I value at more than the annual fee.
The information and associated card details on this page for the Marriott Bonvoy American Express Card have been collected independently by OMAAT and have not been reviewed or provided by the card issuer.
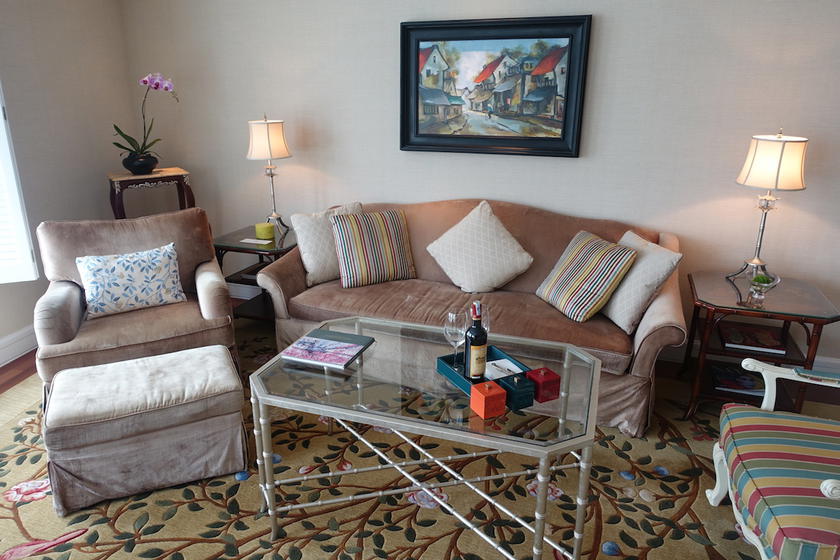
Last year I used my certificate at the Park Hyatt Saigon
The IHG Rewards Club Select Credit Card and IHG Rewards Premier Credit Card (which have annual fees of $49 and $150, respectively) offer an anniversary-free night certificate valid at a property retailing for up to 40,000 points per night. I value that at way more than the annual fee.
The information and associated card details on this page for the IHG Rewards Club Select Credit Card have been collected independently by OMAAT and have not been reviewed or provided by the card issuer.
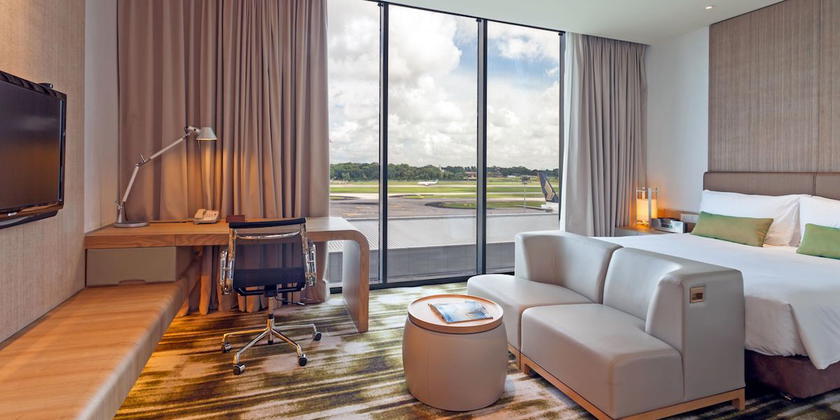
Redeem your certificate at the Crowne Plaza Changi Airport
The Radisson Rewards Premier Signature Visa Card offers an annual bonus of 40,000 Radisson Rewards points, which I value at more than the $75 annual fee. I am just building up a balance at this point, but I imagine at some point I’ll find a good use for them.
The JetBlue Plus Card has a $99 annual fee, and offers 5,000 point bonus on the account anniversary every year, plus a 10% refund on redemptions, and I think that more or less makes it breakeven with the annual fee. On top of that you can get free bags when flying JetBlue, which is how the value of this card quickly adds up.
Annual fees I allocate to credit card spend
This brings me to the cards that I have for actually maximizing my credit card spend. First, to cover the cards mentioned in the previous section, the Platinum Card® is hugely valuable to me, given that it offers 5x points on airfare purchased directly with airlines, though fortunately, I don’t even have to account for that benefit with the annual fee due to the other perks.
The Chase Sapphire Reserve offers 8x points on Chase Travel℠ bookings, 4x points on direct flight & hotel bookings, and 3x points on dining allowing me to maximize the points I earn on three other Chase no annual fee cards (covered below).
The AAdvantage Aviator Silver Mastercard is a tricky one. While I don’t really want to spend money on an American Airlines card, spending $50,000 on the card per year earns me 6,000 elite qualifying dollars, 10,000 elite qualifying miles, and a companion certificate. I’m still not sure I should be doing this, but for I used the card last year and this year, and it has a $195 annual fee.
Then the Amex EveryDay Preferred Card offers 3x points on the first $6,000 spent annually at US supermarkets, 2x points at US gas stations, and a 50% points bonus when you make 30 transactions per billing cycle, so in the end I find that to be worth it for the $95 annual fee.
The information and associated card details on this page for the Amex EveryDay Preferred Credit Card have been collected independently by OMAAT and have not been reviewed or provided by the card issuer.
Then there are the following four no annual fee cards that I have to help me maximize spend:
- The Blue Business® Plus Credit Card from American Express — 2x Membership Rewards points per dollar on the first $50,000 spent annually (1x after that)
- Ink Business Cash Credit Card — 5x points on the first $25,000 spent annually at office supply stores, and on cellular phone, landline, internet, and cable TV services, and 2x points on the first $25,000 spent annually at gas stations and restaurants; points can be combined with Ultimate Rewards points earned on other cards
- Chase Freedom Flex® — 5x points in rotating quarterly categories on up to $1,500 in combined purchases each quarter you activate, and these points can be combined with Ultimate Rewards points earned on other cards
- Chase Freedom Unlimited — 1.5x points in non-bonused categories, and these points can be combined with Ultimate Rewards points earned on other cards
And that’s it!
Bottom line
Yes, I pay a lot in annual fees, but I also get a ton of value out of the cards I have. This includes some pretty awesome perks, from free hotel nights to access to all kinds of lounges. For the most part that covers the annual fees on my cards.
The way I view it, the only two cards where I’m really paying directly for maximizing my spend are the Chase Sapphire Reserve and Amex EveryDay Preferred Card. I’d like to think I get a disproportionate amount of value from those cards too.
Obviously, all of this math is a bit fuzzy, since there are different ways to go about calculating the value you get from cards. Hopefully, this is at least an interesting look at how I approach things.
The information and associated card details on this page for the Amex EveryDay Preferred Credit Card have been collected independently by OMAAT and have not been reviewed or provided by the card issuer.
The following links will direct you to the rates and fees for mentioned American Express Cards. These include: The Blue Business® Plus Credit Card from American Express (Rates & Fees), American Express Platinum Card® (Rates & Fees), and Marriott Bonvoy Business® American Express® Card (Rates & Fees).


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.