United Q2 2025 Financial Results: Optimism On “Less Uncertain” Future

2025 has been a turbulent year so far for airlines, particularly in the United States, given the economic uncertainty that we’ve seen. Airlines are now starting to report their Q2 2025 earnings results, and issue their forecasts for the rest of the year, and there are always some interesting details here.

Last week, Delta Air Lines was the first major US airline to report its financial results. Delta’s stock surged following the announcement, as the company had a more optimistic outlook for the rest of the year than expected. Now United Airlines has become the second major US airline to report its results. The results are good, given all that has been going on, but investors don’t seem overjoyed, as United’s stock is down pre-market.
United reports reasonably good financial results

United has reported its Q2 2025 financial results, and has shared that it sees a positive inflection in both supply and demand for Q3 2025. Profits were a little higher than expected, while revenue was a little lower than expected. For Q2 2025, the airline reported:

  • Operating revenue of $15.2 billion, up 1.7% compared to $15 billion in Q2 2024
  • An operating margin of 11.6%, down 11% compared to 13.1% in Q2 2024
  • Net income of $973 million, down 26% compared to $1.3 billion in Q2 2024
  • Earnings per share of $2.97, down 25% compared to $3.96 in Q2 2024
  • Total revenue per air seat mile of 18.06 cents, down 4% compared to $18.81 in Q2 2024
  • Operating expenses of $10.4 billion, up 8% compared to $9.6 billion in Q2 2024

Given what a global airline United is, it’s interesting to take a look at performance by region, as a few things stand out:

  • The Pacific saw both the most absolute growth in terms of revenue (8.7%), and even saw growth in revenue per available seat mile (2.9%), which is impressive
  • We’ve heard a lot about airlines struggling domestically, and that’s reflected here, with United seeing a 0.7% decrease in total revenue, and a 7% decrease in yields
  • In all other regions, we saw absolute revenue increase, while we saw yields decrease, which is more or less in line with the industry trend
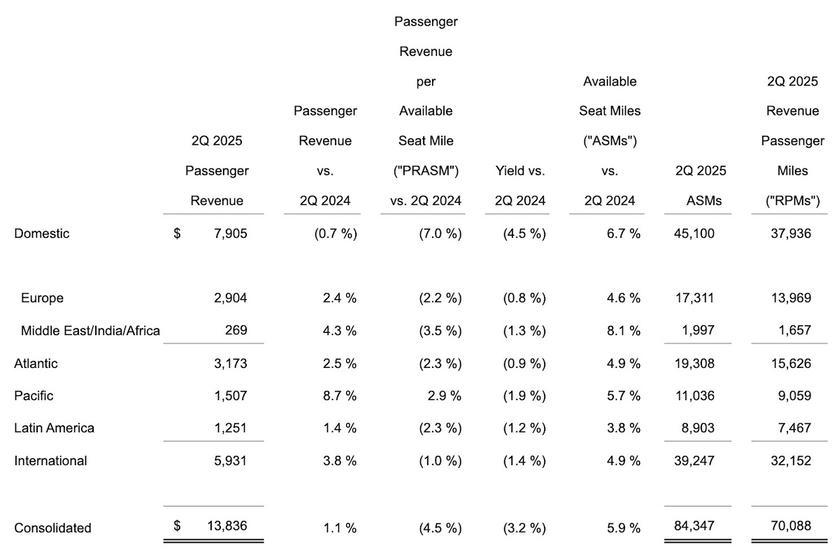
United’s performance by region

United highlights how compared to the same quarter last year, premium cabin revenue grew 5.6%, basic economy revenue grew 1.7%, and loyalty program revenue grew 8.7%. As you’d expect, challenges at Newark negatively impacted the carrier’s performance — United believes this impacted its Q2 2025 pretax margin by 1.2 points, and that it will impact the Q3 2025 pretax margin by 0.9 points.

Here’s how United CEO Scott Kirby describes these results:

“Our second-quarter performance was more proof that the United Next strategy is working. I am extremely proud of the team for executing a strong operation and navigating through a volatile macroeconomic period, while still growing earnings and pre-tax margin for the first half of the year. Importantly, United saw a positive shift in demand beginning in early July, and, like 2024, anticipates another inflection in industry supply in mid-August. The world is less uncertain today than it was during the first six months of 2025 and that gives us confidence about a strong finish to the year.”
United reported a Q2 2025 profit of nearly $1 billion

United upbeat about future, “less uncertain” world

As you can see above, United CEO Scott Kirby is upbeat about the rest of the year, claiming “the world is less uncertain” now than it was for the first six months of the year.

Specifically, United claims that in early July, the company has seen a sequential six point acceleration in demand and a double digit acceleration in business demand compared to the second quarter. The airline is attributing this to less geopolitical and macroeconomic uncertainty.

United has updated its full year guidance for earnings per share of $9-11, which the airline claims reflects the resilience of United’s “brand-loyal, revenue-diverse business model.” Earlier this year, before all of the uncertainty, United was forecasting earnings per share of $11.50-13.50.

The claim of a sudden increase in demand as of early July for both leisure and business demand is quite interesting, and I’m curious what’s driving that. Also, I think the description of the world being “less uncertain” is a good way to put it.

It’s certainly not “certain,” with everything seemingly just being pushed down the road by several weeks, and continued geopolitical unrest. But I suppose it’s less uncertain than it was at the beginning of the year…
United is optimistic about Q3 2025

Bottom line

United has reported its Q2 2025 financial results. The results are roughly what was expected, factoring in the general uncertainty, plus the mess at Newark. As we’ve come to expect, domestic yields were down, and most other regions saw absolute revenue growth, but a decline in yields. The Pacific was the only market to see both revenue and yields increase.

The most interesting revelation from United is its confidence in Q3 2025, and the claim that as of early July, the airline is seeing an increase in demand.

What do you make of United’s Q2 2025 financial results?

Conversations (20)
The comments on this page have not been provided, reviewed, approved or otherwise endorsed by any advertiser, and it is not an advertiser's responsibility to ensure posts and/or questions are answered.
Comment as a member

Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.

Type your response here.

If you'd like to participate in the discussion, please adhere to our commenting guidelines. Anyone can comment, and your email address will not be published. Register to save your unique username and earn special OMAAT reputation perks!

  1. Loading comments…
Recent Comments
The latest from the OMAAT community.

The comments on this page have not been provided, reviewed, approved or otherwise endorsed by any advertiser, and it is not an advertiser's responsibility to ensure posts and/or questions are answered.

Tim Dunn Diamond

As is typically the case, Jeremy jumps in and argues against points that I didn’t make because he can’t accept the bottom line conclusions that I have made and he can’t accept. Having a dozen other people jump in support does not change the reality that he is arguing things I did not say while failing to address realities and conclusion which are absolutely factual. 1. The simple reality is that UA’s RASM deterioration was worse than DL’s and might be the worst among the big 4. UA stated very publicly that its goal was to aggressively grow its domestic system and take out a bunch of low cost carriers in the process. UA still generates over 1 billion less dollars in domestic revenue per quarter and its international size did not offset its smaller domestic size. DL is also adding domestic capacity but is able to offset domestic weakness with international growth and ancillary revenue. 2. DL IS GROWING its international network and has announced enough international routes to significantly cut into UA’s international network advantage including to the Arab Middle East, India and additional flights to Israel. DL is starting LAX-HKG and ORD because it has customers that want it and there simply are no comparably large adds that UA can make. DL IS GROWING ITS INTERNATIONAL NETWORK MORE SUCCESSFULLY THAN UA IS GROWING ITS DOMESTIC NETWORK, a reality which I said years ago would happen. 3. UA has benefited from low labor costs due to open labor contracts which have boosted its profits. The first of those is beginning to hit UA’s finances and there will be many more. 4. UA fans love to tout passenger revenue growth and size even though UA flies more ASMs than DL in every global region. UA simply cannot translate that higher capacity into higher profits on a system basis. Refinery revenue is a GAAP item but DL excludes it for comparison; UA tried and failed to acquire its own refinery. UA has had the same opportunity to build an industry-leading credit card and loyalty program but has trailed DL because they focused on the wrong things for those programs – international revenue. 5. DL is set to extend not only its lead over UA in LAX and NYC but also to add major corporate contracts in Chicago, further extending DL’s position as carrying the most corporate contract revenue. 6. The fall of EWR operationally was bound to happen and spring of 2025 was the point when it finally occurred. It is doubtful that UA will ever return to the size at EWR it was before EWR runway construction began. My statement is completely accurate that 2024 was likely the high point of UA’s quest to match DL’s profits. They were living on borrowed time in many ways and hoping that DL would remain docile which is clearly not happening.

0
‼ 0
Jeremy Guest

@Tim Dunn stop trying to manipulate and provide incorrect financial analysis by throwing a wall of text. You selectively provide information and have a ton of conjectures w/o any data and withhold data when it doesn't support your claims: Your claim: Based on the revenue by region, UA increased domestic capacity by 7% and domestic passenger revenue fell by 0.7% with a decline in RASM that may well lead the big 4. Full context: In a vacuum the first part of that statement is accurate. But what about DL? DL increased domestic capacity by 4% and saw a 1% decline in domestic passenger revenue. As Cranky showed, DL and UA had identical stage-length adjusted PRASM declines domestically in Q1 when accounting for UA's larger capacity increase although there appears to be a slight yield gap in Q2. It's worth noting that not all carriers are seeing this SLA-adjusted PRASM decline in Q1. WN, AS, and F9 saw increases while AA's decrease was smaller (albeit with less capacity added). This negates DL and UA's claim that premium sales are offsetting main cabin issues - domestically the net result even if premium cabin is holding strong is lower yields. Your claim: UA is twice as large as DL in Asia/Pacific - UA flies more TPAC capacity than ANY airline so DL is much closer to the size of the largest airlines than UA, UA is about 25% larger in Latin America, and DL's TATL system is as large as UA's just to Europe. UA breaks out the Middle East and India which is not a DOT reportable region. By the time you factor in all of the routes that DL has announced or says are coming - ATL-DEL, ATL-RUH, ATL-TLV, LAX-HKG - DL will be as large as UA in the TATL region and growing TPAC at a faster rate. Full context: Passenger rev - Q1 + Q2 2025: Domestic: DL: $17.4B UA: $15.1B Atlantic: UA: $4.9B DL: $4.2B - take out MENA + India from UA and that's only ~$0.5B - also DL offers flights to Africa included in its Atlantic revenue, so you would also have to remove ~$0.2B from DL. UA is ~10-15% larger than DL to Europe Pacific: UA: $3.0B DL: $1.4B Latin America: UA: $2.7B DL: $2.3B Capacity growth - Q1 and Q2: Domestic: DL (+4%, +4%); UA (8%, 7%) - UA growing faster than DL domestically but both growing Atlantic: DL (-3%, +4%); UA w/o MENA + India: (flat; +5%); total UA: (-1%; +5%) Pacific: DL (+16%, +11%); UA: (flat, +6%) Latin America: DL (+8%, -1%); UA: (+6%, +4%) Yield growth - Q1 and Q2: Domestic: DL (+1%, -1%); UA: (flat, -4.5%) Atlantic: DL (+5%, -2%); UA w/o MENA + India: (+5%, -1%); UA total (+6%, -1%) Pacific: DL (-7%, -6%); UA: (flat, -2%) Latin America: DL (flat, flat); UA: (+3%, -1%) So, UA is not struggling any bit more adding capacity domestically than DL is adding capacity on the Pacific. DL has added slightly less capacity than UA to TATL and the gap is only technically narrowing in the Pacific where DL is taking hits to yields to add capacity. DL has announced its new routes earlier than UA, but UA is taking more plane deliveries this year and expects next year to be similar. We'll see how capacity growth ends up, but your claims are complete conjecture.

3
‼ 0
Dim Tunn Guest

here we go again

0
‼ 0
Ryan Guest

So basically people were being over dramatic and they expect a surge in demand for leisure and business demand got it.

0
‼ 0
Tim Dunn Diamond

to correct your commentary based on the revenue by region, UA increased domestic capacity by 7% and domestic passenger revenue fell by 0.7% with a decline in RASM that may well lead the big 4. They have had as a key strategic goal for years to grow their domestic system and have made repeated statements about the failing low cost and ultra low cost carrier model. in the international market, UA's RASM decline across the Atlantic and to Latin America was larger than DL's. UA's bright spot is Asia/Pacific but DL is growing Asia/Pacific capacity faster than UA. in comparing size of the two's regions, UA is twice as large as DL in Asia/Pacific - UA flies more TPAC capacity than ANY airline so DL is much closer to the size of the largest airlines than UA, UA is about 25% larger in Latin America, and DL's TATL system is as large as UA's just to Europe. UA breaks out the Middle East and India which is not a DOT reportable region. By the time you factor in all of the routes that DL has announced or says are coming - ATL-DEL, ATL-RUH, ATL-TLV, LAX-HKG - DL will be as large as UA in the TATL region and growing TPAC at a faster rate. The bottom line is that, as I have said many times before, it would be harder for UA to grow into the domestic marketplace than it would be for DL to grow in international markets and this data shows it. notable also is that UA says the EWR meltdown and last minute capacity cuts cost it over a couple hundred million dollars in revenue for the quarter and will impact 3rd quarter (current) revenue but by a lesser amount. from a cost side, UA is beginning to pay the price for borrowing from labor post covid to sustain its growth. It recorded a $561 million charge for the FA settlement - which they will reverse IF the FAs reject the contract. UA still has FIVE MORE labor contracts to settle assuming the FAs vote in their contract proposal. and UA lowered its yearly guidance after touting how great its forecasting ability was when DAL and other airlines and companies pulled their yearly guidance after "liberation day" tariffs were announced. UA provided two sets of guidance, the lower of which was for a recessionary situation - which has not happened. I have said before and will say again that 2024 was likely the closest that UA would come to matching DL's earnings. UA cannot grow its domestic network at the pace it is doing while DL is growing its international network and doing so with better revenue results. UA's labor costs will rise faster than the industry while the smaller airlines that UA thinks it will kill have not died and even when they do, their death will benefit other airlines more than UA. AA and WN will report their finances next and it is likely that they will have more optimistic stories to tell than UA.

1
‼ 0

Save posts to read later

Saving posts is a member feature. Become an OMAAT member to build a reading list you can come back to from any device.

Become a member
Meet Ben Schlappig, OMAAT Founder
5,883,136 Miles Traveled

43,914,800 Words Written

47,187 Posts Published