
A longtime OMAAT reader messaged me an interesting question, which is something I’ve been wondering about as well. I figure it makes for an interesting discussion…
US airlines don’t really directly make money flying
Here’s an interesting question about the fact that even profitable US airlines don’t directly make money transporting passengers:
I’ve been sitting on this question for a while and was wondering if you had any thoughts. Earlier this year, it was reported that CASM (cost per available seat mile) for American, Delta, Southwest, and United, was higher than RASM (revenue per available seat mile) in 2024. While that’s partially due to aircraft shortages in some cases, that’s still not great.
Obviously, they were profitable because of their credit cards and frequent flyer programs, and that’s where my question starts. As points continue to get devalued, lounges get increasingly packed, and elite status gets harder to attain (and requires more credit spending, if getting status just from credit cards), can airlines count on their frequent flyer programs as their main revenue generators in the long run, or will they will need to look elsewhere?
If so, where do you see airlines turning to? It seems unlikely they could turn these type of profits just from flying alone.
I’d also add that as a result of frequent increases in requirements to earn elite status, devaluations in the value of actually having elite status, and award redemption devaluations, airlines face another headwind, which is that they’ve probably caused a lot of folks in their 20s and 30s to become “free agents” when it comes to airline loyalty (as they’ve only really traveled in an era with declining value in being loyal to a specific airline), which could cause the value of frequent flyer programs to decline over time as well.
In 2024, the “big four” US carriers had over $200 billion in revenue, and combined, they had net income of around $8 billion, and operating income of around $14 billion. All four airlines had higher CASM than RASM. United was the closest to breaking even (16.7 cents CASM vs. 16.66 cents RASM), while Delta was the most profitable, but had quite a gap (19.3 cents CASM vs. 17.65 cents RASM).
Of course, the reality of the “big four” US carriers essentially earning their profits through non-flying means makes it tough to maintain a competitive airline industry. Smaller airlines don’t get the same opportunities with their frequent flyer programs, so how are the supposed to compete, and turn a fair profit?
It’s worth noting that this is all still a fairly new trend. Pre-pandemic, RASM was higher than CASM at profitable US airlines. However, we’ve seen a massive increase in costs (particularly labor costs), and this has changed the economics of the industry.
One way that airlines are improving their CASM is by flying larger, more fuel efficient jets, like the A321neo. While that helps with costs, it also means there are more seats to fill, and that can be a challenge in some markets, and puts downward pressure on fares.
What does this reality mean for the future of airlines?
I find this all to be an excellent question, and I don’t actually have a great answer, other than saying that I have the same question. I guess a few thoughts come to mind:
- At this point, airline labor costs are unlikely to decrease, and if anything, they’ll keep going up, given that newly negotiated contracts include incremental pay increases in the coming years
- The major US carriers aren’t even directly making money flying passengers during what I’d consider to be among the best of times, and that says nothing of the potential impact of any sort of an economic downturn
- Consumers often like to label airlines as greedy, and that’s not fair, as this is one of the most difficult industries in the world; I think we sometimes see poor decisions made by airline executives, but the airline industry is hardly greedy
I don’t think airlines will be able to reinvent themselves in any sort of a meaningful way, beyond just continuing to do everything possible to monetize their customer base. I mean, you know it’s a tough time for the industry when Southwest, the United States’ most long term profitable airline, throws in the towel and says “hey, let’s be just like everyone else,” while not having first class or long haul flying.
The way I view it, the future of US airline profitability comes down to two things…
I think more industry consolidation is inevitable
I know it’s not a popular take, but I think that one way that industry unprofitability will be addressed is through further consolidation. There’s a general belief out there that “oh, industry consolidation is done, and a thing of the past.” However, consolidation has been happening for decades, and I think it will continue to be the case going forward.
There’s simply not room in the market for so many players all trying to undercut one another, with increasingly limited differentiation (look at Southwest copying the business models of other carriers, all while ultra low cost carriers try to become more full service). Airfare will need to go up somewhat.
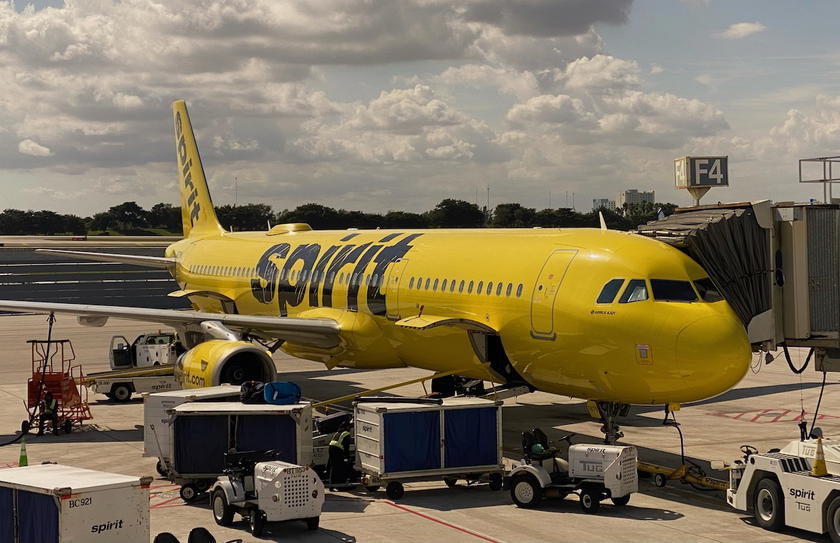
Take Spirit, as an example. JetBlue tried to take over the airline, and that takeover was ultimately blocked by regulators, in order to preserve competition in the industry. But an airline can only have a negative 20% operating margin for so long, before something’s gotta give. Of course we all want low fares, but shareholders can only subsidize those for so long, before bankruptcy comes knocking…
Airlines will keep trying to monetize their customers
Frequent flyer programs started as a cost center to get people to be loyal to an airline, but of course they’ve taken on a life of their own, and have now become the most profitable part of US airlines. Ultimately airlines have access to a huge membership base, and there are all kinds of things they can market to members. Of course credit cards are the most profitable, but there are other opportunities as well.
So I think airlines will keep trying to do that. However, personally I’m a bit more skeptical of airlines’ ambitions to grow their loyalty revenue. Some US airlines expect that their frequent flyer program revenue will increase by up to 50% in the coming years, and I just don’t think that’s realistic.
On the one hand, interest in travel is probably at an all-time high in recent years, and there are more people willing to splurge and spend their disposable income on premium travel experiences. On the other hand, consumers have a lot more choices, and the increased profitability of airline frequent flyer programs is contingent on consumers acting irrationally:
- Airline elite status just isn’t worth as much as it used to be, with upgrades so hard to come by; that eliminates a huge incentive to earn status
- We’re increasingly seeing people use cards that belong to the major non-airline points ecosystems, where you can redeem rewards efficiently toward the paid cost of a ticket, rather than just earning miles, and that offers lots more flexibility
- Redeeming miles in general is becoming more difficult, and as airlines increasingly switch to dynamic and revenue based award pricing, the incentive to be loyal to an airline decreases
Personally, I think we’re reaching the point of market saturation when it comes to the growth possibilities for airline frequent flyer program profitability. There are so many airlines competing not just with one another, but also with other products outside the airline frequent flyer program ecosystem.
Don’t get me wrong, I’m not suggesting airline frequent flyer programs will collapse, and suddenly become unprofitable. However, I don’t think we’re going to see the level of growth that some airline executives are predicting, and are counting on to continue to increase their profits.
One other thing worth mentioning is that there’s always talk among some politicians of trying to cap interchange fees, which would make the credit card industry much less profitable. If that were to ever happen, that would have a massive impact on airlines and consumers, as current credit card agreements are essentially subsidizing airfare.
Bottom line
Nowadays, the major US airlines are earning most of their profits through non-flying means, and in particular, through their lucrative credit card agreements. While this has proven a reliable source of revenue, it presents a challenge, since it’s hard for smaller airlines to compete, as a profitable loyalty program requires scale.
So, will US airlines have to reinvent themselves? Personally, I’m not sure what their next amazing innovation could be, other than continuing to monetize their customer base in every way possible. I think the more likely scenario is that we see industry consolidation, and the same cycle continue as before.
How do you see all of this playing out?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.