
In late September I outlined my credit card strategy, and how October was a month of credit card applications for me. Well, I just picked up my second card, and wanted to share my experience with that.
Recapping My First Card Application For October
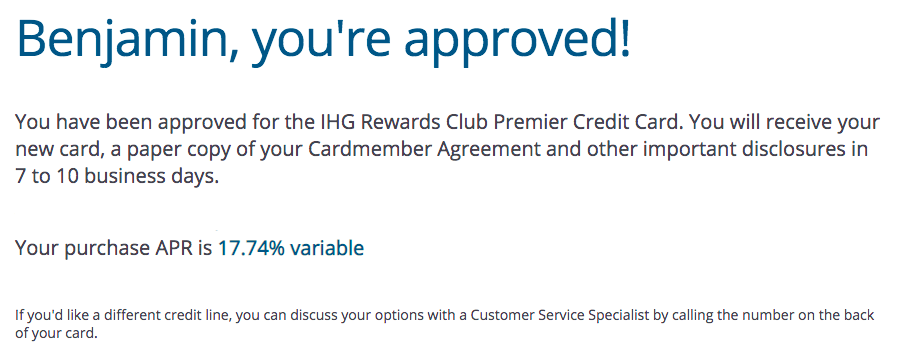
On October 1 I applied for the IHG One Rewards Premier Credit Card (review), which is the card I’ve wanted most. Much to my surprise, I got instantly approved (which is rare for me with Chase cards).
My Second Credit Card Application
The Citi Double Cash® Card (review) will be my new credit card for everyday spending. As of recently, rewards earned on this card can be converted into ThankYou points. Going forward this no annual fee card will earn 2x ThankYou points per dollar spent (1 when I purchase and 1 when I pay), so this for me will replace the Chase Freedom Unlimited® (review) for everyday spending.
I applied for this card on October 2, and initially got a message saying my application was under review and that they needed further information. They gave me an application ID and a number to call.
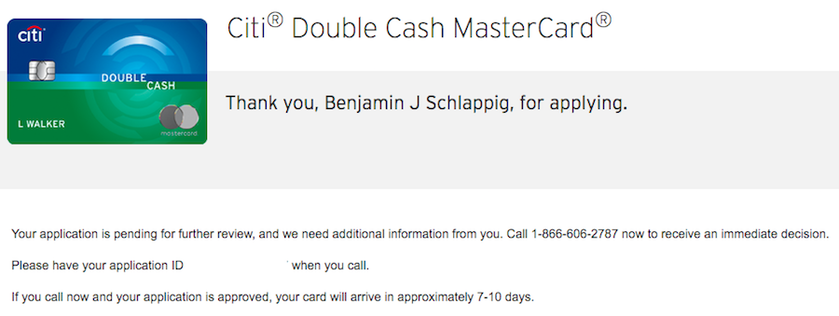
I called the number, and they told me that I had to move around some of my credit line from other cards. That’s fair enough, since I have some Citi cards with outrageously high credit limits.
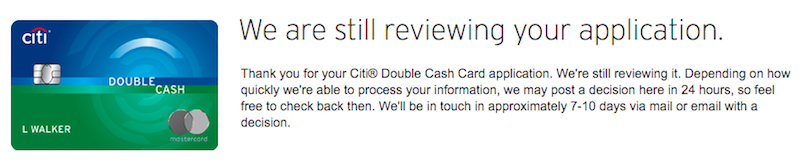
I was conditionally approved, though I was told a more senior person would still have to sign off on the application, and that could take several days. I just checked the status again and it still shows as being under review, though I trust that will come through.
This Card Will Be A Game Changer For Me
I value Membership Rewards, Ultimate Rewards, and ThankYou points roughly equally, at about 1.7 cents each. So to me, this is the best personal credit card for everyday spending. In addition to using this card for my “normal” spending:
- I’ll be paying my taxes with this card at a fee of 1.87%, which is like acquiring ThankYou points for ~0.94 cents each
- I’ll even likely use Plastiq for many of my bills at a maximum fee of 2.5% (though they often have promotions that lower the rate); even so, I think it’s worth acquiring ThankYou points at ~1.25 cents each
What’s Next?
I have two trains of thought here.
I’d really like to still get the Southwest® Rapid Rewards® Performance Business Credit Card (review), which has an incredible welcome bonus and valuable long term perks when flying Southwest:
- Initially, I was going to apply for the Southwest Card and then the IHG Card, but then I learned the IHG offer ended first, so I decided to apply for that first
- I was at 4/24 when I applied for the IHG Card so I should be at 5/24 now (this is in reference to the “5/24 limit”)
- However, my credit report doesn’t show that latest inquiry, and I think often there is a delay there of a few weeks
Does anyone know if there’s still a chance I’d be approved for the Southwest Card under those circumstances?
Bottom Line
I’m thrilled to have been approved for the IHG One Rewards Premier Credit Card, and to more or less have been approved for the Citi Double Cash® Card. The IHG offer ends soon and has been on my radar for a long time, while the recent changes to the Citi Double Cash make it a no brainer for me.
I hope to be approved for the Southwest® Rapid Rewards® Performance Business Credit Card next, but even if that doesn’t happen I’d still be happy.


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.