
Investment platform Robinhood is launching a credit card, and it almost sounds too good to be true.
Details of the lucrative Robinhood Gold Card
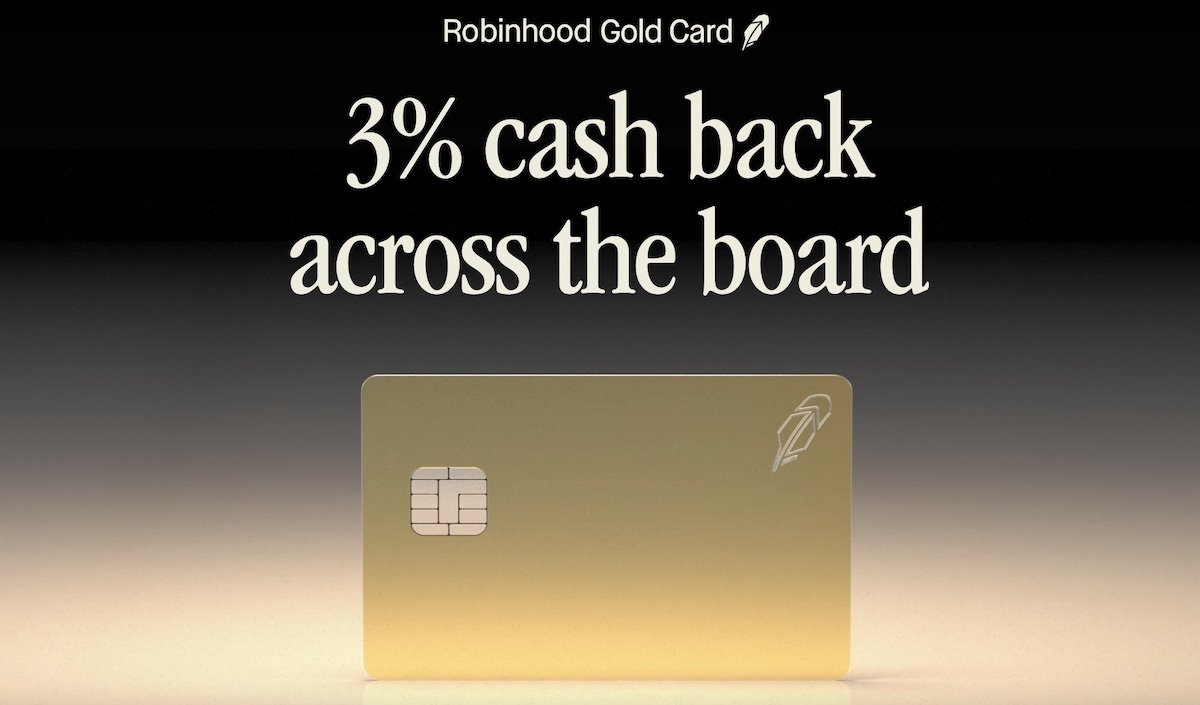
The Robinhood Gold Card will soon be coming to market, issued as a Visa Signature Card. The card isn’t yet open for applications, but you can add yourself to the waitlist, with a launch expected later this year. The card has a very simple value proposition, as it will offer 3% cash back on all purchases with no caps. That’s quite literally unheard of, and obviously sounds too good to be true.
To cover some more of the details of the Robinhood Gold Card:
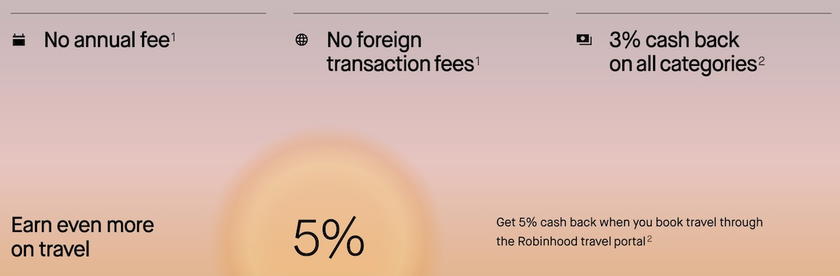
- The card will offer 3% cash back on all purchases, and 5% cash back on travel booked through Robinhood’s travel portal, all with no foreign transaction fees
- The card will let you redeem cash back in a variety of ways, including transferring the rewards to your Robinhood brokerage account, booking travel through Robinhood’s travel portal, shopping with partner merchants, and more
- The card won’t have an annual fee, but you’ll need to be a Robinhood Gold member to get the card, with a membership costing either $5 per month or $50 per year
- The card will weigh 17 grams and will be made of stainless steel; meanwhile if you refer 10 people to Robinhood Gold, you’ll receive a “limited edition Solid Gold Card”
- The card will offer a variety of Visa Signature perks, including trip interruption protection, auto rental collision damage waiver, extended warranty protection, travel and emergency assistance, and more
It’s interesting to note that last year, Robinhood acquired credit card startup X1 for $95 million, and it appears that this credit card launch is essentially based on that concept.
Is the Robinhood Gold Card too good to be true?
Over the years we’ve seen credit card rewards get richer and richer. While there are lots of ways to earn travel rewards with credit cards, at a minimum you should be earning the equivalent of 2% cash back on all purchases, or else you’re leaving money on the table.
However, the concept of a 3% cash back credit card with no caps is unheard of. That’s more than the merchant fees, meaning that Robinhood would be losing money on every single transaction, rather than making money. Is there any world in which a loss leading credit card like this is sustainable?
On the one hand, there’s potentially still quite a bit of upside for Robinhood:
- This will encourage people to become Robinhood Gold members, which costs at least $50 per year, so think of that as an indirect annual fee
- Many credit cards offer huge upfront sign-up bonuses, while I suppose one could argue that Robinhood is instead allocating that investment into ongoing rewards
- This would certainly help Robinhood build huge market share as an investment platform, since this is a card that many people would probably be interested in
- Some people will finance charges, which is another way that credit card companies ordinarily make money
- The average person isn’t spending hundreds of thousands of dollars per year on credit cards, so the company’s per-person loss on the card will be minimal for most customers
On the other hand, this really does sound too good to be true. I mean, you can pay your federal income taxes by credit card with a fee of under 2%, so you could profit more than 1% on your tax payments.
Then again, for those of us who are savvy with using credit cards, this card might not get us a higher overall return than we have by using a credit card portfolio that takes advantage of bonus categories. But for everyday, non-bonused spending, this level of return is unheard of.
Let’s wait and see when this card launches, as I can’t help but wonder if there might be some surprises.
Bottom line
Robinhood is planning on launching the Gold Card later in 2024, which will offer 3% cash back on all purchases with no caps. This is an unheard of return on everyday spending, and Robinhood would lose money on each transaction.
It’s interesting to see an investment platform essentially try to make a credit card a loss leader in order to get people on the platform. I’ll reserve final judgment until the card launches, but I sure am intrigued…
What do you make of the Robinhood Gold Card?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.