Making Travel Less Taxing: Introduction
Your Tax Home (Away from Home)
Airfare and Transportation
Lodging and Meals
Entertaining Clients
Car Expenses
The Nitty Gritty: Required Receipts and Tax Forms
Ask Scott!
As discussed last week, I am guest blogging through tax filing season to highlight opportunities to reduce your tax liability with business travel expenses. In last week’s introduction, I discussed the main requirements for deducting your business travel expenses: travel must be unreimbursed and incurred in the ordinary and necessary course of running a business. This week, I’ll discuss the last requirement for travel to be deductible: expenses must be incurred while traveling away from home. Please note the legal disclaimer at the end of this post.
A Second Home, Courtesy of the IRS
“Where is home?” When asked this question at a cocktail party, you will likely answer with either your current place of residence or where you grew up. For frequent business travelers, the ever-complicating helpful IRS would also like to give you a second home—a tax home. According to the IRS, business travel is deductible when your business requires that you be away from your home substantially longer than your normal work hours. The key criteria here is that your work must be taking you away from your “tax home.”
For the vast majority of taxpayers, their tax home is the same as their personal home, but for those who do extensive business away from their personal home, the two may be different. The distinction is important because only those expenses incurred while away from your tax home are deductible. Your tax home is the place where you normally conduct your business, regardless of where you live.
So, hypothetically speaking, for the random road warrior who travels to Ft. Worth each week for work but returns to a personal residence in the Phoenix area on the weekends, his tax home would be Ft. Worth even though he calls Phoenix home. If you have more than one place of business, then your tax home is the place where the majority of your business is conducted. For most taxpayers, the calculus for determining a tax home stops there.
But, if you have no primary place of business, the IRS lovingly refers to you as an itinerant, which to me sounds vaguely like a travel blogger. 🙂 If the IRS classifies you as an itinerant, then you are never away from home, which means none of your travel expenses would qualify as business deductions, so even the most enthusiastic “I’m never home” business traveler is best served tax-wise to have a tax home. Here are the three factors the IRS will consider in determining your tax home when you have no primary place of business:
- You perform part of your business in the area of your main home and use that home for lodging while doing business in the area;
- You have living expenses at your main home that you duplicate because your business requires you to be away from that home;
- You have not abandoned the area in which both your historical place of lodging and your claimed main home are located; you have a member or members of your family living at your main home; or you often use that home for lodging.
If you meet all three factors, your tax home is your personal home, and any travel you incur away from there will clear the “away from home” requirement for business travel deductions. If you meet two of the three factors, you may have a tax home depending on the facts and circumstances (which is IRS-speak for “hire a good tax attorney”). If only one factor applies to you, then you have no true tax home, and none of your business expenses are deductible, unfortunately.
Temporary and Long Term Job Assignments
A temporary assignment (see, e.g., visiting professors, traveling nurses, or oil field workers, among other vocations) on an ongoing basis may cause a change in your tax home depending on the length of the assignment. If, upon taking the job, you expect that it will last for more than one year, the job is considered to be indefinite, and your tax home would change to that location immediately. The IRS considers a job that you expect to last for 12 months or less to be a temporary assignment that does not shift your tax home, thereby making your travel expenses deductible. Thus, all other things equal, a 12 month appointment in a different location is tax preferred to a 13 month one.
During law school, a visiting law professor of mine was delighted to explain to his eager tax students how he was deducting all his living expenses in Charlottesville, Virginia, for the year in which he and his entire family were away from his tax home of Ann Arbor, Michigan. Because his temporary assignment was expected to last for less than 1 year, he was considered to be traveling away from his tax home and all of his lodging and meals were deductible (subject to other limits which I’ll discuss in later weeks). If he had taken the visiting professorship with an understanding from the dean that it was going to be a permanent position, then his tax home would have shifted immediately since his expectation at the time would be that the job assignment would last longer than 12 months. (He in fact returned to Ann Arbor, tax savings in tow).
Where There’s an Expense, There’s (Potential) Income
While it does not matter to the IRS in which state you work, individual states do have a stake where you work. A few commenters brought up state income tax allocation issues last week. So, I thought I’d address that issue briefly here since if you’re traveling away from home on business and incurring expenses, you are hopefully also generating some income while doing so. If not, your days in business may be as numbered as the latest merged airline credit card offer.
If you travel and conduct business in multiple states, you may need to allocate your income among those states. A full discussion of all 50 states’ income allocation rules is of course beyond the scope of this post, but in brief, state tax officials are no fools and won’t take pity on tax evasion.
The tax departments in high-tax states like California and New York know that every person traveling there on business has an incentive to allocate income away from their grasp. If you work in multiple states, your economic incentive is to allocate as much income as legally possible to the low or no tax states in which you also work.
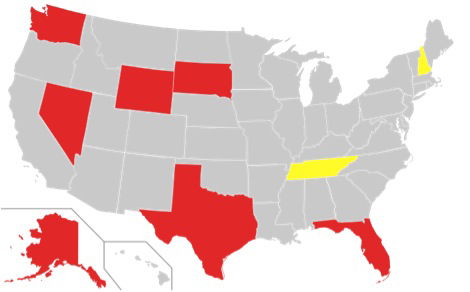
States With No State Income Tax on Wages (NH and TN Tax Investment Income But Not Wages)
If you own real property, the state income allocation is fairly easy: whatever income received from the rental or sale of the property would be taxable in the state in which the property is located. But, what about those who generate income from services? Most famously, NFL players must allocate their income earned based on the days they are in various cities, and since the game schedules are publicly available, any diligent state tax collector is sure to come calling if, for example, Joe Flacco doesn’t include some Louisiana income in his 2013 tax return after his lights-out performance in the Super Bowl.
For those of you with less public lives, what’s the test? Each state differs slightly, but the primary inquiry is whether you perform services in the state or receive income related to a business carried on in the state. For example, if you traveled to New York to meet with a client and made a sale, but you performed all of the work in Washington, then you may escape New York taxation since you did not in fact perform the work while there.
Conclusion and Next Time
Thus, your home for tax purposes turns out to be less than intuitive but quite important to determining whether specific expenses become deductible or not. Feel free to use “where’s your tax home, good lookin’?” as a pick-up line at your next cocktail party and share with us the results in the comments. Next week, I’ll discuss how much you can deduct for airfare when traveling on a part-business, part-personal trip or when redeeming frequent flyer miles for business trips. Please leave any questions you have in the comments! Also, you may follow me on Twitter @ScottTaxLaw or learn more about my legal and CPA practice.
Disclaimer: While I hope the information I provide will be helpful (and hopefully even humorous at times), none of this information should be construed as offering legal advice or creating an attorney-client relationship between the reader and my law firm. You should not act or refrain from acting based on this advice and should consult your own attorney or CPA regarding your specific tax matters. IRS Circular 230 Notice: Nothing in these communication is intended to be used and cannot be used by a taxpayer for the purpose of avoiding penalties that may be imposed by law.


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.