
JetBlue is obviously in a tough financial spot. The airline hasn’t turned a profit since before the pandemic, and is approaching $9 billion in debt, which is just not sustainable in the long run. It sure seems like a trip into Chapter 11 bankruptcy is in the cards — the CEO has insisted it won’t happen in 2026, but I think that’s about the only thing that can be promised.
Anyway, JetBlue has just released its Q3 2026 results, and there’s quite a bit of optimism in there… including a claim that JetBlue will turn an operating profit in 2027?!
JetBlue losses widen, but airline claims 2027 will be different
JetBlue has posted a net loss of $257 million in Q3 2026, with an operating loss of $144 million, meaning the operating margin was negative 5.1%. Admittedly it has been a tough year for all carriers, given the increase in jet fuel prices. While airlines have been able to increase fares somewhat, it hasn’t been enough to fully offset the increase in costs.
For context, below are JetBlue’s operating income and margin over the past seven quarters, since the beginning of 2025. That amounts to close to $900 million in operating losses over seven quarters.
| Quarter | Operating income | Operating margin |
|---|---|---|
| Q1 2025 | -$174M | -8.2% |
| Q2 2025 | +$6M | +0.3% |
| Q3 2025 | -$100M | -4.3% |
| Q4 2025 | -$100M | -4.5% |
| Q1 2026 | -$224M | -10.0% |
| Q2 2026 | -$141M | -5.2% |
| Q3 2026 | -$144M | -5.1% |
While JetBlue’s stock has been in a downward spiral in recent times, given the likely possibility of a Chapter 11 filing, the carrier’s Q3 2026 release are sending the stock up significantly pre-market, despite a slight revenue and earnings per share miss.
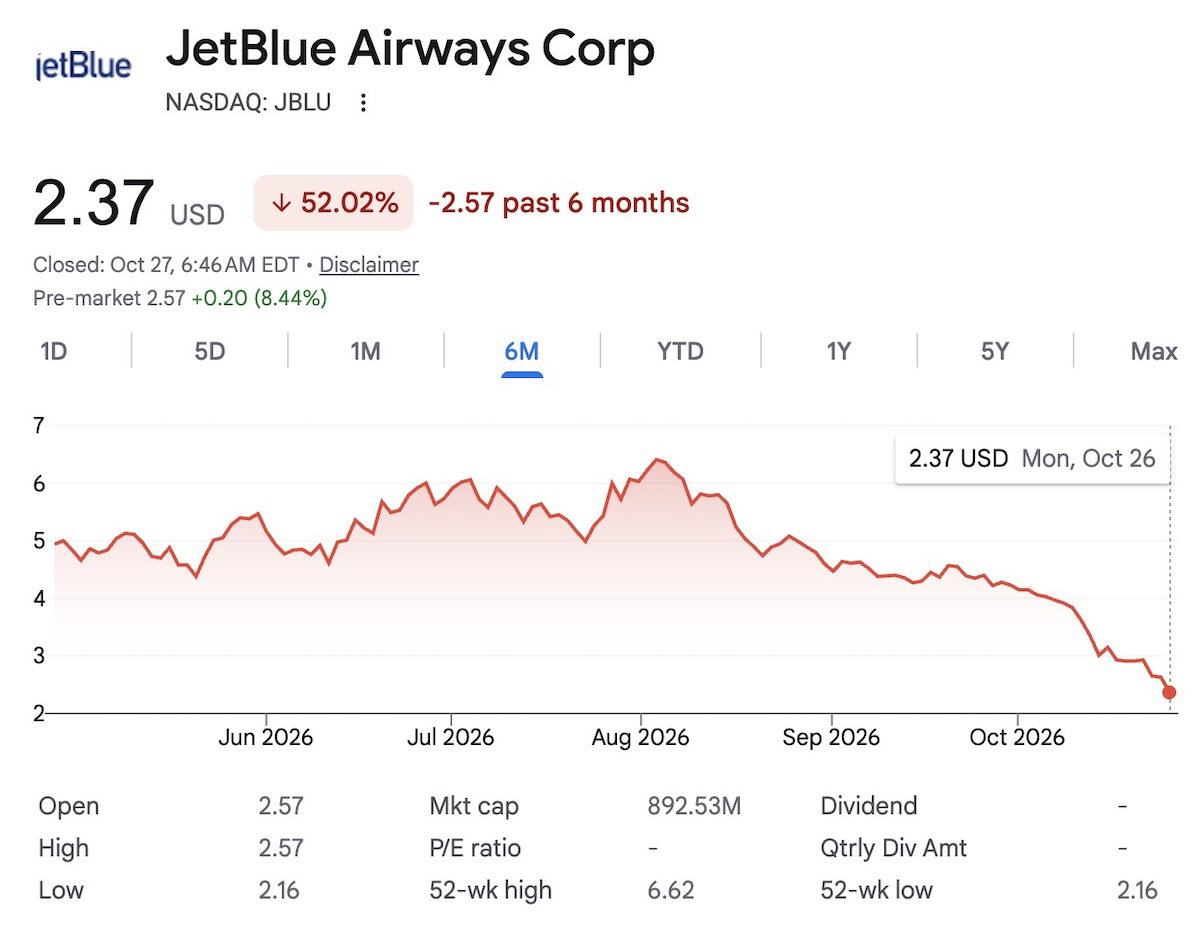
What’s the great news from JetBlue? Well, CEO Joanna Geraghty is confident the airline will turn an operating profit in 2027:
“I’m very encouraged by the progress we made in the third quarter. Resilient demand and strong yields drove revenue well ahead of our initial expectations, allowing us to recapture more of the increase in fuel costs than we initially expected. That momentum has carried into the fourth quarter, and Fort Lauderdale continues to deliver exceptional results even as we significantly grow capacity.”
“We delivered year-over-year adjusted operating margin improvement in the third quarter and expect further expansion in the fourth quarter even with higher fuel prices. Together with continued JetForward execution, this reinforces our confidence in achieving sustained operating profitability in 2027 and delivering at least $1 EPS and positive free cash flow in 2028.”
Let me emphasize that an operating profit and a net profit are not the same thing. JetBlue is currently paying around $600 million per year in interest expenses. However, an operating profit would of course be major progress. The question is, is this just baseless optimism on the part of JetBlue, or what’s going on?
Help me understand the math on JetBlue’s turnaround?
It’s of course great to claim that the airline will turn an operating profit in 2027, though the math isn’t really mathing for me here. Yes, I think JetBlue is making some generally positive changes, like rolling out first class, and increasingly leaning into its loyalty program, including opening lounges.
However, the carrier’s margins are (understandably) getting worse rather than better, so I don’t really see how anyone can make the claim about profitability in 2027, other than just pure hope and optimism.
Broadly speaking, it feels like many industry executives are basically taking the approach of thinking that jet fuel prices will decrease materially, all while airlines will be able to maintain the fare increases they’ve been able to push through since the start of the war.
I do feel like JetBlue management has lost a bit of credibility when it comes to their claims about JetForward and profitability. In early 2025, the company’s CFO claimed the airline expected to reach a positive operating margin in 2025. Obviously that didn’t happen.
Then in early 2026, the company’s management said it expected a breakeven or positive operating margin for 2026. Obviously that didn’t happen either. Admittedly many issues were due to macro trends beyond the carrier’s control, but that’s also just a reality of the industry.
So I’d view the 2027 operating profit goal as being one based on perfect macro conditions, with airlines able to maintain the same pricing power with much lower fuel prices. This is overly simplistic, but just to put this into perspective:
- In the first three quarters of 2026, American had revenue of $47 billion, an operating income of $521 million, and an operating margin of 1.1%
- In the first three quarters of 2026, JetBlue had revenue of $7.75 billion, an operating income of -$509 million, and an operating margin of -6.6%
If we were to assume that both airlines saw a 6.6% increase in operating margins, American would have an operating profit of over $3.6 billion, putting it in Delta’s league. Those are some fanciful projections, eh?
Bottom line
JetBlue’s Q3 2026 margins worsened, which isn’t surprising, given the impact of jet fuel prices on airlines. What I find interesting is that JetBlue executives claim the airline will turn an operating profit in 2027. Admittedly they’ve been trying to make these claims for a couple of years now, but I just struggle to follow that logic, unless we’re to believe that jet fuel prices will go down materially, while airlines will be able to maintain fare increases.
Operating profit or not, JetBlue will have to find a way to shed its debt, if it ever stands a chance of turning a net profit, given how much it’s paying to service its nearly $9 billion in debt.
What do you make of JetBlue’s 2027 profitability claims?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.