
US Bank has launched a new credit card, which potentially offers 4% cash back on everyday spending. We’ve never seen a card that’s potentially quite this rewarding for all purchases, though as you’d expect, there are some hoops to jump through. Should this card be in your wallet?
Basics of the US Bank Smartly Visa Signature Card
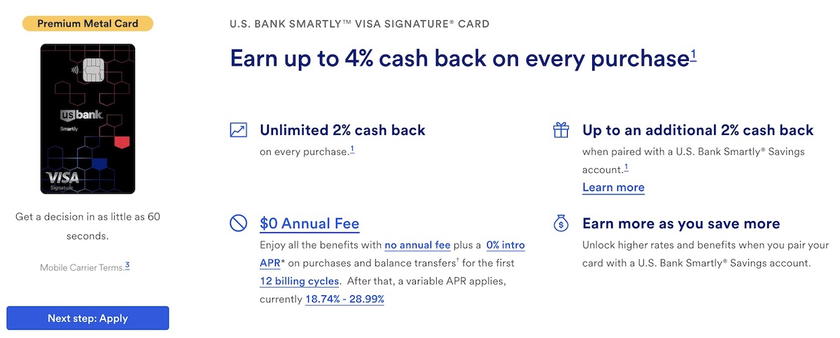
The US Bank Smartly Visa Signature Card has no annual fee, and offers unlimited 2% cash back on all eligible purchases. In and of itself, earning 2% back is basically the gold standard of credit card rewards, and is the least that anyone should settle for.
Note that the card does have foreign transactions fees, and also doesn’t have a sign-up bonus, so those are two downsides.
What’s exciting is that the card potentially gets way more rewarding than offering 2% cash back. That’s because you can get a better return if you have a US Bank Smartly Savings account, plus average daily combined qualifying balance in a US Bank deposit, trust, or investment account:
- Earn 2.5% cash back on spending if you have a qualifying balance of $5,000-49,999
- Earn 3% cash back on spending if you have a qualifying balance of $50,000-99,999
- Earn 4% cash back on spending if you have a qualifying balance of $100,000+
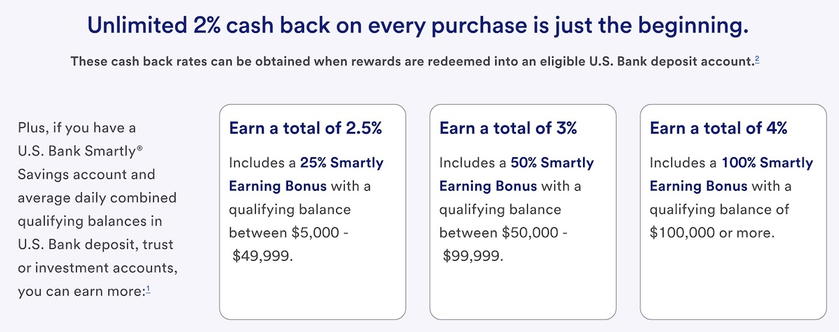
As you can see, you can potentially earn 4% cash back on all purchases, with no caps. If you are in a position to deposit that type of cash with US Bank, what’s the most efficient way to do so? Obviously you don’t just want to park cash in an account earning an uncompetitive interest rate.
You do need to open a US Bank Smartly Savings Account. While this potentially has decent interest rates (with a balance of $25,000+), it would appear that an annual investment or IRA account would be the best way to park money with US Bank with limited opportunity cost.
The catch is that this comes with a $50 annual fee, unless you have at least $250,000 invested, in which case there’s no fee. Some people may be able to move over their IRA with little opportunity cost, in which case that could be a great deal.
Is this up to 4% cash back card worth it?
It really is incredible how far credit card rewards have come over the years. The thought of earning 4% cash back on everyday spending is basically unheard of. Just as an example, you can pay income taxes by credit card for a fee of under 2%, so you could basically earn a 2%+ “profit” on your tax payments by using this card. That’s kind of wild.
Admittedly this card isn’t for everyone, and the key to it being worthwhile is having cash that you can move around with a low opportunity cost. If you an investment account or IRA and you’re able to move it around without giving up much, then this is a worthwhile opportunity, if you ask me.
A few thoughts on the concept of earning 4% cash back, and this overall value proposition:
- I do sort of wonder if this is almost too good to be true, and if we could see US Bank start to add restrictions, like capping rewards, restricting tax payments (even though it’s a totally legitimate form of credit card spending), etc.
- While you can probably get a better return with points cards for purchases in bonus categories (like dining, groceries, etc.), earning 4% cash back on everyday spending is unheard of, and in a completely different league
- Being able to earn 4% cash back should really make us reframe how we view earning miles & points, and the opportunity cost of doing so
- If you’re not a huge credit card spender, then it’s probably not worth jumping through the hoops to get this card, while if you’re a big spender, this card could earn you a lot of rewards
Bottom line
The new no annual fee US Bank Smartly Visa Signature Card offers 2% cash back. While that’s pretty good, what makes this card exceptional is that it offers up to an additional 2% cash back if you maintain a certain balance with US Bank. For those with at least $100K with US Bank, you could receive 4% cash back on all purchases.
This card won’t be for everyone, but it’s at least worth being aware of…
What do you make of US Bank’s new credit card?


Membership is free and takes no more information than commenting as a guest. Earn status points for good contributions, and see fewer ads as your status grows.